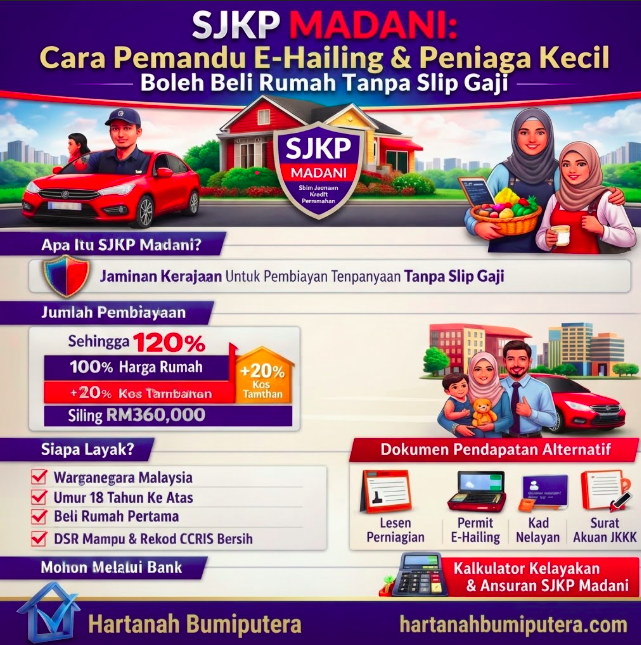
Many e-hailing drivers, small business owners, fishermen, and other gig workers in Malaysia have stable monthly incomes, but their housing loan applications are still rejected because they do not have traditional payslips or EPF statements, which banks usually require. This is not because they are unable to afford it, but because conventional bank assessment systems are built for permanent employees. The Madani Housing Credit Guarantee Scheme (SJKP Madani) is specifically designed to close this gap. This article explains how it works, who is eligible, and how you can estimate your own eligibility before going to the bank.
What is SJKP Madani?
SJKP Madani is a government housing credit guarantee scheme that allows banks to approve home financing for borrowers with irregular incomes, including gig workers, small business owners, fishermen, and self-employed individuals, even without traditional payslips. It is not a direct loan from the government; instead, the government guarantees a portion of the financing risk to the bank, making the bank more confident to approve applications that would previously have been rejected simply due to non-conventional income documentation. Under the 2026 Budget, the funding for this scheme has been doubled to RM20 billion, showing the government's priority to continue expanding home ownership access to this group.
How Much Financing Is Eligible?
SJKP Madani offers a guarantee up to 120% of the property purchase price, 100% for the house price itself, and up to 20% additional for related costs such as MRTA/MRTT/CLTA/CLTT, legal fees, valuation fees, and renovation/furnishing costs. However, the total financing amount is limited to a ceiling of RM360,000, regardless of how high the house price you choose. The financing term can be up to 35 years, or across two generations, whichever comes first.
Who Is Eligible?
The main eligibility criteria for SJKP Madani, based on official SJKP and Ministry of Finance information:
- Malaysian citizen, aged 18 years and above
- First-time purchase of a residential property only — not for buying a second or third home
- Debt Service Ratio (DSR) — total repayment of all loans (including new home loans) cannot exceed 65% of monthly gross income
- Clean CCRIS record — no arrears exceeding 2 months in the past 12 months, and no other negative credit records in the past 24 months
- Open to fixed-income OR variable-income — including gig workers and self-employed individuals, not just permanent public/private sector employees
No Pay Slip? Here Are the Accepted Alternative Documents
This is the most important part for gig workers and self-employed individuals — SJKP Madani accepts alternative income proof in place of conventional pay slips, such as:
- Registered business license (for small businesses)
- e-hailing permit or taxi permit (for Grab, InDrive and others drivers)
- Fisherman registration card
- Self-employment confirmation letter or income statement verified by the Village Development and Safety Committee (JKKK), Category A public servant, Village Head/Headman, or Branch Bank Manager
For permanent salary workers who wish to apply through SJKP Madani (for example due to strict DSR or other reasons), salary slips and normal EPF statements will still be accepted as standard home loan applications.
How to Apply?
SJKP Madani is not a product you apply directly to the government, it is a guarantee channeled through banks/financial institutions participating in this scheme, such as BSN, Bank Islam and several other banks. You apply for a housing loan as usual at the bank counter, and state your intention to use SJKP Madani facilities considering your income status. Since the list of participating banks and detailed conditions may change from time to time, please check the official SJKP website or contact your nearest bank branch for the latest information before applying.
Calculate Your Eligibility Before Going to the Bank
Before spending time at the bank, you can estimate yourself whether your financial profile is likely to be eligible, enter the price of the house you are targeting, monthly gross income (average if income is not fixed), and existing monthly commitments into our SJKP Madani Eligibility & Installment Calculator. This calculator will calculate the maximum financing limit (120% of the price or RM360,000 ceiling, whichever is lower), check whether your DSR ratio is within the 65% limit, and estimate your actual monthly installments complete with a PDF report that you can bring along when discussing with bank officers.
Remember: this calculator provides only an illustrative estimate based on DSR and the official SJKP Madani financing limit — it does not replace actual bank approval, which also evaluates CCRIS records, credit history and individual character. If your estimate shows that you are not eligible, try to reduce existing monthly commitments first (e.g., settle small credit card balances) using our Debt Consolidation & Debt Settlement Calculator before reapplying.
Looking for your first home? View current property listings at https://www.hartanahbumiputera.com/hartanah, or if you are interested in Bumiputera properties, explore Bumiputera Lot and Malay Reserved Land to understand the land status before making a decision.




