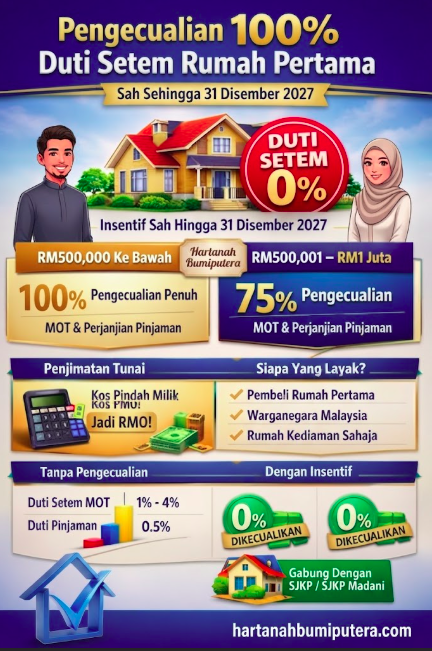
Stamp duty often becomes one of the largest cash costs that homebuyers need to prepare during the transfer process, aside from the deposit. The government continues to extend the exemption incentive for first-time homebuyers as an incentive for home ownership, and now this incentive is valid until 31 December 2027.
How Much Exemption Are You Eligible For?
- Properties valued up to RM500,000 — 100% FULL exemption on both stamp duty for the Memorandum of Transfer (MOT) and loan agreement stamp duty
- Properties valued from RM500,001 to RM1 million — 75% exemption on both types of stamp duty
This means that for a first-time homebuyer purchasing a RM400,000 property, the MOT and loan agreement stamp duties, which would normally amount to thousands of ringgit, can be reduced to zero, a significant cash saving that can be used for other costs such as legal fees, MRTA insurance or renovation.
Who Is Eligible?
This incentive is specifically targeted at first-time residential property buyers, those who have never owned any residential property in their own name. The property must be for residential use (not commercial), and the transaction must be carried out within the period when the incentive is in effect.
This Stamp Duty Is Different From Normal Stamp Duty
Without exceptions, MOT stamp duty is calculated according to a graduated rate (1%-4% depending on the property price), while loan agreement stamp duty is usually 0.5% of the loan amount. For buyers who are NOT eligible for the exemption (example: second home, or price exceeding RM1 million), estimate the actual cost using our Stamp Duty Transfer Calculator and Stamp Duty Loan Agreement Calculator, both calculators also automatically display estimates after the first home exemption based on the house price you enter.
Aside from stamp duty, you also need to budget for legal fees, use our Legal Fee Calculator to estimate the full legal costs for the Sales Agreement and Loan Agreement.
Combine With Other Incentives
This stamp duty exemption can be combined with other first home incentives such as SJKP/SJKP Madani (if you have no fixed salary slips) and tax exemption on housing loan interest, to maximise the reduction of your overall first home ownership costs.




