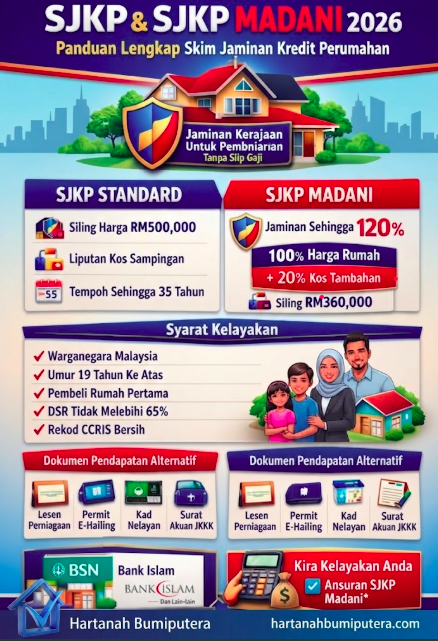
One of the biggest barriers for many Malaysians to own their first home is not their actual financial capability, but income documentation that does not conform to conventional bank formats. The Housing Credit Guarantee Scheme (HCGS), or Housing Credit Guarantee Scheme (HCGS), was specifically designed to address this issue, and has been further expanded under the 2026 Budget with a much larger guarantee capacity. This article explains the two main variants of this scheme, Standard HCGS and Madani HCGS — as well as how to calculate your own eligibility.
What is HCGS?
HCGS is not a direct loan from the government. It is a credit guarantee offered by the government to banks/financial institutions, reducing the risk for banks when approving home financing to borrowers who do not have a fixed salary slip, including e-hailing drivers, small traders, fishermen and self-employed workers. Under the 2026 Budget, the guarantee capacity of this scheme is reported to have been significantly expanded to allow more such borrowers to obtain bank approvals that were previously difficult to obtain.
Standard HCGS vs Madani HCGS: What's the Difference?
Both variants share the same goal but target different housing price segments:
- SJKP Standard — targeted for higher-value properties, up to a price ceiling of around RM500,000, with loan coverage also including additional costs besides the house price itself.
- SJKP Madani — targeted for low and moderate-income homes, offering guarantees up to 120% of the purchase price (100% house price + up to 20% additional costs such as MRTA/MRTT, legal fees, valuation fees and renovation costs), with a loan amount ceiling of RM360,000 according to official SJKP information.
Both schemes allow a loan tenure of up to 35 years or spanning two generations, whichever comes first, and require the purchase of a first-time home only.
Who Is Eligible?
- Malaysian citizens, aged 18 years and above
- First-time homebuyers
- Debt Service Ratio (DSR) not exceeding 65% of monthly gross income
- Clean CCRIS record (no overdue payments exceeding 2 months in the past 12 months)
- Open to both permanent and non-permanent income, alternative documents such as business licenses, e-hailing permits or income confirmation letters verified by JKKK/Headman/Bank Manager are accepted for gig workers and self-employed individuals
Calculate Your Eligibility
Before going to the bank, estimate your own financing limit, monthly instalments, and your DSR status using our SJKP Madani Eligibility & Instalment Calculator, complete with a PDF report that you can bring along when discussing with the bank officer. If you also want to know the expected stamp duty and legal fees, try our Stamp Duty Transfer Calculator and Legal Fee Calculator.
For official information and the latest list of participating banks, please refer to the official SJKP website. Once you are sure about your eligibility, view the current property options at https://www.hartanahbumiputera.com/hartanah.




