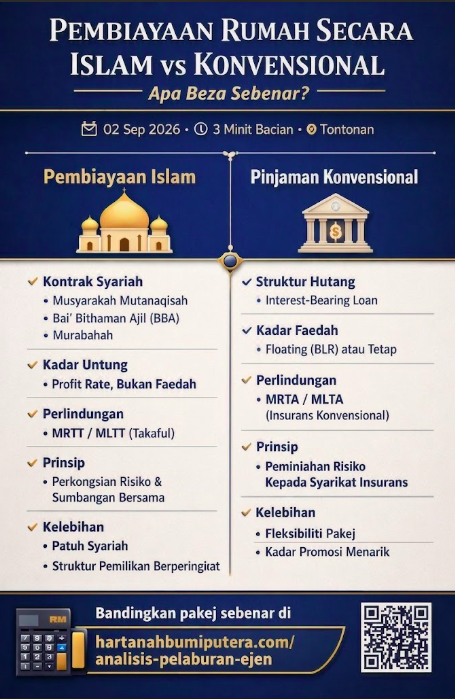
"Islamic homes" and "conventional homes", both types of financing allow you to buy the same house, but the structures behind the scenes are very different. Understanding the real differences, not just the labels, helps you make more informed choices, without being misled by often confusing rumours.
Conventional Loan — Interest-Based Debt Structure
Conventional housing loans operate based on a simple interest-bearing loan concept: the bank lends you money to buy a house, and you repay the loan along with interest charged on the outstanding loan balance each month. The interest rate can be floating, according to the bank's Base Lending Rate, or fixed for a certain period.
Islamic Financing — Based on Shariah Contracts
Islamic home financing, on the other hand, does not directly use the "interest-bearing loan" concept, instead it is structured based on contracts that comply with Shariah. The two most commonly used structures in Malaysia today are:
- Musyarakah Mutanaqisah (Diminishing Partnership) — the most popular structure for Islamic home financing today. The bank and buyer initially "own" the property as partners. The buyer gradually buys out the bank's share through monthly payments, while also paying rent (ujrah) on the portion still owned by the bank. Over time, the bank's ownership share diminishes until the buyer owns 100% of the property.
- Bai' Bithaman Ajil (BBA) / Murabahah — a cost-plus-profit sale structure that was historically more commonly used. The bank buys the property and resells it to the buyer at a price that includes a fixed profit margin, paid in installments over an agreed period.
Profit Rate vs Interest Rate — Is One Cheaper?
From a calculation perspective, conventional loans charge an "interest rate" while Islamic financing charges a "profit rate" — different names, but both determine how much extra cost you pay above the principal amount borrowed/financed. Practically, in the same market rate environment, the monthly installment payments for Islamic and conventional financing are usually quite comparable for similar terms and rates, there's no guarantee that one type is always cheaper than the other. The actual difference often depends on the specific bank package, current promotions, and the rate structure offered, not just because it's "Islamic" or "conventional".
Variable Rate (BLR/BFR) vs Fixed Rate — Available in Both Types
Another common misconception is assuming that Islamic products must be fixed rate and conventional products must be variable. In reality, both types of financing offer variable rate options — linked to the Base Lending Rate (BLR) for conventional, or Base Financing Rate (BFR) for Islamic, both of which move in line with the Overnight Policy Rate of BNM, or fixed rate packages, depending on the product and bank you choose. Therefore, the choice between "Islamic vs conventional" and the choice between "fixed rate vs variable rate" are actually two separate decisions that need to be evaluated separately.
Insurance/Takaful Mortgage — Another Structural Difference
A structural difference also exists in the insurance protection usually bundled with home financing. Conventional loans are typically bundled with MRTA/MLTA (conventional life insurance), while Islamic financing is usually bundled with equivalent products based on Takaful, MRTT (Mortgage Reducing Term Takaful) or MLTT. The concept is similar in terms of purpose (protecting the outstanding loan/financing in case of death or permanent disability), but the structure behind them also differs, with Takaful operating on the principle of shared contribution (tabarru') and risk sharing among participants, compared to the conventional insurance model which is based on risk transfer to the insurance company. Premiums/contributions for both need to be quoted separately according to your age profile and term.
Simple Illustration Example
As a rough estimate (not an actual quotation): for a RM360,000 financing over a 30-year period with a rate of approximately 4% per annum, whether labelled as interest rate or profit rate — the monthly instalment using the standard reducing balance method will produce almost the same figure whether it is a conventional product or an Islamic product structured as Musharakah Mutanaqisah, because both calculate payments based on the outstanding balance each month.
The significant difference only arises if one product uses a flat-rate structure (such as some old BBA) compared to reducing balance — the flat-rate structure tends to result in a higher total cost compared to reducing balance at the same nominal rate, because profit is calculated on the original principal amount throughout the term, not the decreasing balance.
What You Should Actually Compare
Instead of choosing purely based on the label "Islamic" or "conventional", compare the actual figures: effective profit/interest rate, monthly instalment amount, total cost over the term, flexibility of early payment (redemption), and whether the product is Full-Flexi/Semi-Flexi which allows your excess funds to offset the loan balance. Both Islamic and conventional banks offer variations of this product.
To see how different profit/interest rates affect your actual monthly instalments, try our loan comparison calculator at /analisis-pelaburan-ejen to compare packages numerically before making a decision.




