Auction properties are often considered "golden opportunities" to get a house at a price below market value, and in some cases, this is true. However, the process of buying auction properties is very different from normal purchases through real estate agents, and it carries risks that you need to fully understand before placing a deposit. This guide explains the basics of the auction process so that you can enter with open eyes.
Why Properties End Up at Auction?
Most auction properties are the result of bank repossessions, i.e., when the original owner fails to pay housing loan instalments within the set period, and the bank takes legal action to sell the property to settle the outstanding debt. In addition, there are also properties that end up at auction due to other legal proceedings, such as court orders related to property division or creditor claims. Understanding why a property is at auction can help you assess the situation better, although this is not always detailed in the advertisements.
Where Auction Properties Are Advertised
Auction properties are usually advertised through several channels:
- Advertisements in mainstream newspapers (usually on specific days each week for the legal/auction section).
- Websites of auctioneers appointed to manage the sale.
- Websites of banks that hold the property as collateral, which usually also list the latest auction properties under their property/collateral portals.
When viewing listings, pay attention to important information such as the date and location of the auction, reserve price, and contact details of the lawyer or auctioneer handling the case.
Deposit and Reserve Price
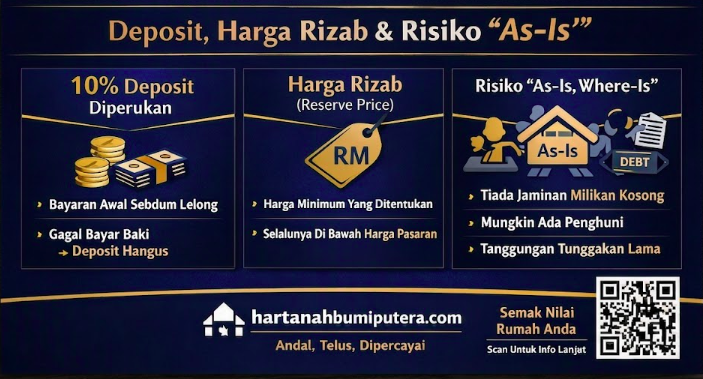
To participate in an auction and bid, you need to pay an initial deposit (earnest deposit) — typically around 10% of the reserve price, although the exact amount may vary depending on the auctioneer's firm or bank involved, so always check the specific terms for each auction. The reserve price is the minimum price set, and bids must start from or exceed this price to be valid.
The most important thing to understand: if you win a bid but then fail to complete the remaining payment within the specified period, the deposit you have paid is usually forfeited. Therefore, make sure you are truly financially prepared before bidding, not just "taking a chance".
Buy "As-Is" — No Guarantee of Vacant Possession
Unlike regular purchases through a standard Sale and Purchase Agreement (SPA), auctioned properties are typically sold "as-is, where-is" — meaning you are buying the property in its current condition without the right to a thorough inspection before bidding, and without a full guarantee that you will gain vacant possession immediately after winning. Some auctioned properties are still occupied by existing occupants, and the process of removing the occupants (if necessary) can take time and involve additional proceedings.
Furthermore, auctioned properties sometimes have outstanding utility bills or land/tax arrears that were not settled by the previous owner, and as a new owner, you may inherit the responsibility of settling these arrears depending on the specific sale conditions. This is why it is important to check the full status of the property before bidding, not after winning the bid.
Payment Period for the Balance After Winning the Bid
After successfully winning the bid, you are usually given a specific period to settle the remaining full price, typically within 90 to 120 days, although the actual period depends on the sale conditions and can vary between cases. This means if you plan to finance the purchase through a bank loan, you need to act quickly to apply and obtain loan approval within this limited period, something that is more challenging compared to regular purchases which usually have more time available.
Cautious Steps Before Bidding
- Involve an experienced lawyer in auction property matters — they can help check the sale conditions (Proclamation of Sale) and explain the specific risks of the case.
- Conduct a title search at the land office to ensure the title status, encumbrances, and whether there are any mortgages or caveats on the property.
- If possible, try to gain access to view the external condition of the property before the auction, although full inspections are usually not allowed.
- Prepare financing earlier — discuss with the bank about the possibility of pre-approval for a loan so that you do not miss out on time after winning.
Auction properties can be a good opportunity for buyers who are prepared and understand the risks involved, but it's not for everyone — especially first-time homebuyers who are not familiar with the property legal process. If you're just starting to explore the world of property and want to understand the basics of costs and the normal purchase process before attempting the more complex auction route, read other guides first on hartanahbumiputera.com to build a solid foundation of knowledge.




