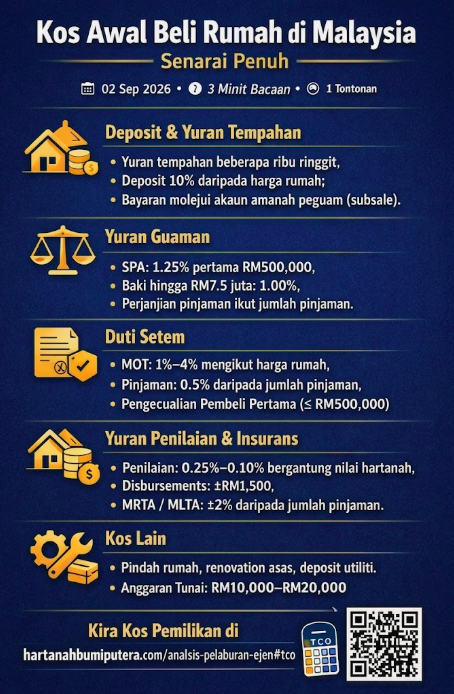
Many homebuyers are only willing to pay a 10% deposit, and are surprised to find that they need to prepare additional cash for various fees and duties before the house keys are handed over. Below is a full list of initial costs you need to budget for, based on the standard scale and rates used in Malaysia.
Deposit & Booking Fee
Most purchases start with a booking fee, usually a few thousand ringgit or a small portion of the house price, paid to "reserve" the unit before the Sale and Purchase Agreement (SPA) is signed. After that, the remaining portion of the standard 10% deposit, minus the booking fee already paid, needs to be settled when signing the SPA. The exact amount and timeframe depend on the developer/seller's terms.
For sub-sale properties (pre-owned homes, not new developer projects), the deposit sequence is usually slightly different, typically paid directly to the lawyer as a stakeholder through a trust account, and the timeframe to settle the remaining deposit is agreed between the buyer and seller in the SPA, not set by the developer. Always ensure that your deposit is paid to a legitimate lawyer's account and a formal receipt is provided, not directly to an individual.
Legal Fees — SPA & Loan Agreement
Legal fees for the Sale and Purchase Agreement (SPA) are calculated according to the statutory scale under the Solicitors' Remuneration Order 2023 (Perintah Peguam (Kadar Bayaran Peguam) 2023):
- First RM500,000 of the house price: 1.25% (minimum fee RM500)
- Remaining up to RM7.5 million: 1.00%
- Amount exceeding RM7.5 million: negotiable, usually not exceeding 1.00%
Loan agreements with your bank are subject to legal fees calculated using the same scale, but based on the loan amount, not the house price. Some law firms also charge a slight additional fee above this statutory scale, so the actual quoted price may vary slightly between firms.
Stamp Duty — MOT & Loan Agreement
Stamp duty on the Transfer of Ownership Memorandum (MOT) is calculated on a tiered basis according to the house price:
- First RM100,000: 1%
- RM100,001 to RM500,000: 2%
- RM500,001 to RM1,000,000: 3%
- Amounts exceeding RM1,000,000: 4%
Important note: under the 2026 Budget announcement, first-time homebuying Malaysian citizens may be eligible for full exemption of MOT stamp duty for properties valued at RM500,000 and below, subject to eligibility criteria such as the SPA being signed within the exemption period and only one exemption in a lifetime. Confirm your actual eligibility with LHDN or your bank when purchasing.
The loan agreement is subject to stamp duty at a flat rate of 0.5% of the approved loan amount.
Valuation Fees & Pawn Insurance
Your bank will appoint a registered valuer to assess the property, with fees calculated according to a graduated scale — 0.25% for the first RM100,000, decreasing gradually down to as low as 0.10% for larger amounts — subject to a minimum fee of approximately RM300. In addition, disbursements (miscellaneous legal costs such as title search, bankruptcy search, land office registration and others) usually total around RM1,500 altogether.
MRTA or MLTA (life insurance for the loan) is an optional choice at most banks, although some packages require it, with estimated premiums starting around 2%+ of the loan amount — depending on age, loan term and the insurer. Get an accurate quote from your bank or takaful/insurance company for the exact figure.
Other Frequently Forgotten Costs
- Moving costs — hiring a truck/movers, can reach several hundred to several thousand ringgit depending on distance and amount of goods.
- Basic renovation — repainting, installation of lights/fans, curtains, and minor repairs before moving in.
- Utility deposit — Tenaga Nasional, water, and gas require an initial deposit when setting up a new account.
Example Illustration: RM400,000 House
For a rough idea, say you buy a house priced at RM400,000 with a 10% deposit (RM40,000) and a loan of RM360,000. The estimated SPA legal fee is 1.25% of RM400,000 (around RM5,000, subject to actual scale and firm quotation). MOT stamp duty is calculated in stages, 1% on the first RM100,000 and 2% on the remaining RM300,000, making the estimated total around RM7,000 before any first-time buyer exemption is deducted. The loan agreement stamp duty is approximately 0.5% of RM360,000, that is, an estimated RM1,800. Adding valuation fees, disbursements and MRTA, the additional cash costs above the deposit can reach tens of thousands of ringgit, hence it is important for you to calculate the actual figures before signing anything.
These figures are only illustrations based on the scale and official rates explained above; your actual amount depends on the house price, loan amount, eligibility for exemption, and the actual quotations from your lawyer and bank firm.
Since many of these factors depend on the specific house price and your loan package, the most accurate way to get a comprehensive estimate is to use our TCO (Total Cost of Ownership) calculator at /analisis-pelaburan-ejen#tco — enter the actual house price you are targeting for a full breakdown of costs, item by item.




