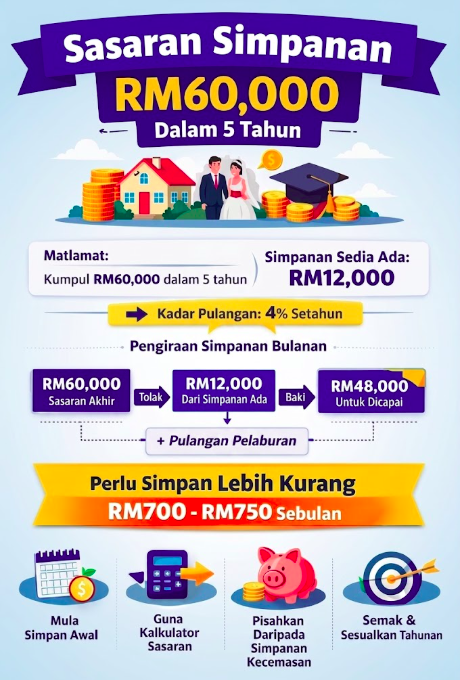
Many people know what they want to achieve financially, such as a home down payment, wedding costs, or children's education funds, but are unsure how much they need to set aside each month to get there. The Savings Target Calculator on HartanahBumiputera flips the usual way of thinking: instead of asking "how much will I have in the future," it asks "how much do I need now to reach my goal."
This approach is suitable for anyone who has a specific financial destination in mind, whether that goal is several years away or getting closer. What's important is that it changes the conversation from the vague and difficult-to-implement "I need to save more," to a concrete number each month that can be directly entered into your personal budget, making the goal much more realistic, easier to track, and easier to maintain momentum throughout your planning period.
Reverse Calculator for Goal Planning
Most savings or investment calculators start with the monthly savings amount, and calculate how much will accumulate by the end of the period. The Savings Target Calculator works in reverse, meaning you start with the target amount you want to achieve, the amount you currently have saved, the time period (in years) until you want to achieve the target, and the expected annual investment return rate (default illustration 4.0% per year).
From this input, the calculator determines what you need to do, that is, an estimate of the additional savings you need to set aside regularly, in order to close the gap between your current savings (which also grow according to the expected rate of return during that period) and the final target you want to achieve in the end.
This approach is very useful for planning specific goals such as a down payment for a house purchase, wedding costs, children's education fund, or any other financial goal where you already know the destination (target amount) and the time frame (target date), but need to know how much monthly savings effort is required to reach there confidently.
This reverse approach also helps avoid a common mistake, which is saving randomly without clear goals, and only realizing after several years that the accumulated amount is still far from sufficient for the intended goal. By knowing early on how much is needed each month, you can adjust your personal budget from now, rather than waiting until the target date is near before realizing the shortfall.
How Your Existing Savings Also Help
One important factor considered by this calculator is that the savings you already have now are not static throughout the period; they also grow according to the expected investment return rate, just like the additional money you save regularly. This means your existing savings also "work" for you, reducing the actual amount of additional savings effort required to reach the final target.
That is why, the earlier you start planning and the more savings you have at the beginning of the period, the lighter the additional savings burden you need to set aside each month, because the effect of existing savings growth also contributes significantly to the final goal, especially for periods longer than several years.
On the contrary, for someone who starts with very little or no existing savings, almost the entire goal needs to be achieved through regular monthly savings, making the monthly burden much higher compared to someone who already has a solid savings base at the beginning of the same period. This shows the importance of starting the habit of saving as early as possible, even with small amounts, because it gives more time for those savings to grow before a major goal needs to be achieved.
Calculation Example: RM60,000 Target in 5 Years
Suppose you want to save RM60,000 as a house deposit, within 5 years from now. You already have RM10,000 set aside, and you expect an annual investment return rate of 4.0% on your savings throughout that period.
Over the 5-year period, your existing RM10,000 savings, if invested at a 4.0% annual return rate, will grow on its own to an estimated RM12,000 to RM12,200 by the end of the period, depending on the compounding frequency used, which is a growth of approximately RM2,000 to RM2,200 without you needing to make any direct additional contributions.
This means, from the overall target of RM60,000, the remaining gap to be covered through additional monthly savings is approximately RM60,000 minus RM12,000 (existing savings growth), i.e. approximately RM48,000, which needs to be accumulated over the 5 years or 60 months, taking into account also the investment returns on those additional monthly savings themselves.
Roughly speaking, without considering the full compounding effect on each monthly saving, this is equivalent to an estimated additional saving range of RM700 to RM750 per month. With the investment returns on monthly savings also taken into account, the actual amount required each month may be slightly lower than this rough estimate, since each initial monthly saving also has time to grow before the 5-year period is fully completed.
Tips For Planning Your Savings Target
- Start as early as possible. The longer the period you give your existing savings and monthly savings to grow, the smaller the monthly savings burden you will ultimately need.
- Use realistic and frugal rates of return, not overly optimistic rates. Rates of return that are higher than reality will cause you to save less than you should.
- Review your goals regularly, especially if the actual cost of your goal, such as house price or wedding cost, changes from your original estimate.
- Separate these goal savings from your regular emergency savings, so that you are not tempted to use your goal funds for unplanned expenses.
- If the required monthly savings amount seems too high, consider extending the goal period, or reducing the final target amount, so that it is more realistic with your current financial capacity.
- Ensure that the savings or investment instruments you choose are suitable for the time horizon and risk level you are comfortable with, because higher rates of return usually also bring higher risk.
- Review these calculations every year, not just once at the beginning. Check whether your savings are on the right track, and adjust your monthly savings amount if there are changes in income, goal costs, or actual rates of return achieved, so that your plan remains relevant and realistic year after year, not just relying on initial assumptions that are never reviewed after a long period has passed.
Planning towards clear financial goals is much easier when you know exactly how much monthly effort is required, compared to simply saving randomly without a clear direction. Use this calculator to test various scenarios for targets, timeframes, and rates of return, so that your savings plan is more realistic and achievable.
Try this calculator for free at Savings Goal Calculator.
Note: This calculation is an illustrative estimate based on a fixed estimated rate of return, and actual investment returns may fluctuate. Please seek advice from a licensed financial advisor before making any savings or investment decisions.




