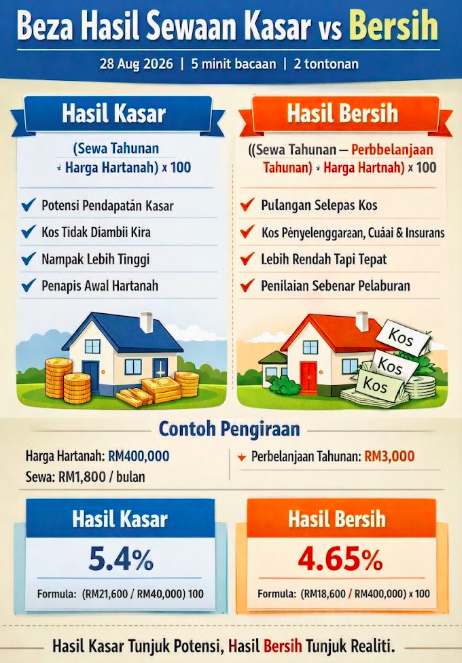
Many future property investors make big decisions based on just one sentence: "this unit can rent for RM1,800 a month, price RM400,000, must be good." The problem is, raw numbers like these don't tell the whole story. That's why the Rental Yield Calculator is important, it gives you two numbers, gross and net, so that you can evaluate a property more honestly before paying a deposit or signing the S&P.
What Is Rental Yield and Why It Is Important
Rental yield is a measure of the annual percentage return a property provides based on the rent received, compared to the price of the property itself. It is not capital appreciation (increase in value) when the property is sold later, it is purely about rental income compared to the purchase price. This number is important because it allows you to compare two different properties fairly, something that cannot be done by just looking at the rental amount in ringgit alone.
This calculator gives two separate numbers: gross yield and net yield. Many property listing sites and agents only mention gross yield because that number looks more attractive. But as an investor, you need to know both to make smart decisions.
Yield is also useful as a quick screening tool before you go further in the buying process.
If you are comparing several areas, for example, a condominium in the city centre versus a terrace house on the outskirts, rental income allows you to place both on the same scale, even though the price and type of property are vastly different. This is why many experienced real estate investors start their analysis with yield figures, not just price or location.
The Real Formula Behind the Calculator
The formula for gross yield is simple:
- Gross Yield (%) = (Annual Rent / Property Price) x 100
Annual rent here is the monthly rent multiplied by 12. This figure is easy to calculate, but it ignores all the costs you need to bear as a landlord. That's why this calculator also calculates net yield, which subtracts annual expenses from annual rent before dividing by the property price:
- Net Yield (%) = ((Annual Rent - Annual Expenses) / Property Price) x 100
These annual expenses include things like maintenance fees and sinking fund (for strata units), door tax and land tax (quit rent and assessment), agent fees when searching for new tenants, minor repair costs, insurance, and vacancy periods when the unit is unrented for several months. Once all of these are subtracted, the resulting figure is usually much lower than the gross yield, and that is the true picture of your return.
Many new investors are surprised when they see the difference between these two figures for the first time. Some assume that a 6% rental yield is good, whereas after deducting the above costs, the actual net yield may only be 4% or less.
Also note that this formula does not take into account financing costs such as monthly loan installments. This is intentional, since rental income is designed to measure the property's performance itself, independent of how it is financed. Someone who buys in full cash and another who takes a 90% loan will get the same rental income for the same property, even though the actual return on their cash is vastly different. Therefore, you need another metric such as Cash-on-Cash Return.
Calculation Example: Condominium RM400,000
Let's use a real example. Suppose you are considering a condominium unit on the outskirts of town priced at RM400,000, and you are confident you can rent it out at a rate of RM1,800 per month.
The first step is to calculate annual rent: RM1,800 x 12 months = RM21,600 per year.
Gross yield: (RM21,600 / RM400,000) x 100 = 5.4%. At first glance, this looks like a fairly good return compared to typical bank deposits.
Now, say the annual expenses for this unit (maintenance fees, door taxes, land taxes, insurance, and estimated small repair costs) amount to RM3,000 per year.
Net yield: ((RM21,600 - RM3,000) / RM400,000) x 100 = (RM18,600 / RM400,000) x 100 = 4.65%.
The difference between 5.4% and 4.65% may seem small on paper, but in actual ringgit terms, it means almost RM3,000 less per year than you might initially expect. If you are comparing several different units, such a difference can determine which option is truly more profitable.
Common Mistakes and Practical Tips
The most common mistake made by new investors is relying solely on the gross yield provided by agents or listing platforms, without considering the actual costs of owning the property. This can surprise you after a few months of ownership when you finally realise how much money has "disappeared" due to small costs that were overlooked initially.
- Don't forget vacancy costs. Even though your unit is always occupied now, assume at least a month empty every one or two years when calculating expenses, this is the reality of the rental market.
- Accurately consider the strata maintenance charges. A luxurious condominium with many amenities usually has higher monthly charges, which can significantly eat into your net profit margin.
- Compare rental income with current market value, not the price you paid before. If you've held the property for a long time and its value has increased, recalculate the yield based on the current market value to know whether your capital is still working hard there, or better transferred to another investment. For an estimate of the current market value, you can also try the Automated Valuation Model (AVM) tool on this site, which estimates value based on actual comparable property transactions.
- Don't compare gross income of one property with net income of another. Make sure you compare equivalent figures, gross with gross, net with net.
- Recheck the rental figures you're using. Agents sometimes give optimistic rental estimates to make the property look more attractive. Check rental listings of comparable units in the same area for a realistic picture, not just assumptions.
- Understand that yield is not the only deciding factor. A property with a low yield but in a rapidly developing location may still be attractive due to long-term capital appreciation potential. Yield is most useful when compared within the same property category and investment strategy.
- Recalculate yield periodically, not just once when buying. Rental market and maintenance costs change from year to year. A property that was great on the day you bought it may no longer be competitive five years later if rents in the area don't keep up with inflation, or if strata maintenance charges continue to rise.
Net rental income is a good starting point, but it does not take into account financing costs such as monthly loan instalment payments. If you are buying using a bank loan, a more relevant figure to understand the return on the actual cash you are investing is Cash-on-Cash Return, which is also provided as a separate calculator on this page.
Tunai-atas-Tunai (Cash-on-Cash Return), which is also provided as a separate calculator on this page.
As a first step, if you are unsure of the actual market value of a property before calculating yield, you can try the Automated Valuation Model (AVM) tool on this page, which estimates value based on actual real estate transactions in the area.
Try this calculator for free at Rental Yield Calculator.
Note: All figures in this article are illustrative estimates for planning purposes only, and are not financial or investment advice. Please consult a licensed financial advisor or conduct further research before making any real estate investment decisions.




