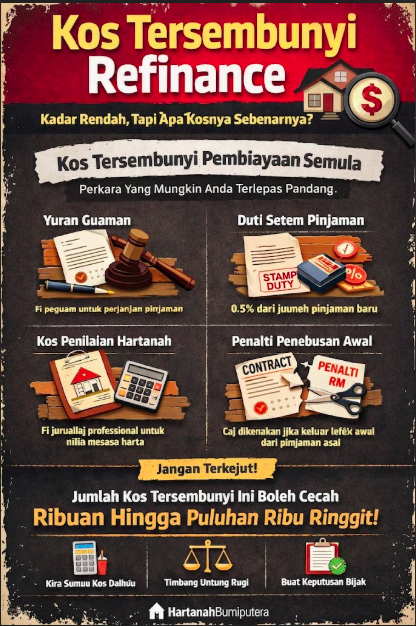
When banks offer a new lower interest rate, the temptation to refinance your home loan is strong. But a lower rate doesn't always mean you'll save money overall, since refinancing also comes with its own costs. The Refinance Savings Calculator on HartanahBumiputera calculates both sides, the interest savings and the actual cost of refinancing, so you can see the full picture before making a decision.
Refinance advertisements from banks usually highlight the new lower rate as the main attraction, but rarely clearly show the actual costs involved in switching from your old loan to a new one. This makes a calculator like this important, because it forces you to look at both sides of the balance, savings and costs, before making any new long-term commitments.
Why a Low Rate Alone Isn't Enough
This calculator compares your existing loan (current rate, remaining loan term) with the new loan offer (new rate, new term), but it doesn't stop there. It also takes into account the actual cost of refinancing, which includes legal fees, loan stamp duty, property valuation fees, and any prepayment penalties imposed by your existing bank for leaving the loan early.
Net savings are calculated by taking the total amount of interest successfully saved over the remaining loan period, minus the total cost of refinancing. This calculator also calculates the breakeven period in months, which is how long it will take for your monthly savings to "cover back" the initial costs that need to be paid to refinance.
Many borrowers only look at the lower monthly instalments without realizing that they need to pay a lump sum upfront to start the process. Legal fees and valuation fees are usually paid before or during the refinancing process, while loan stamp duty is also borne as part of the new transaction costs. Without considering the total cost, someone can be easily misled by the attractive monthly instalment figures, while the actual cost to get there also needs to be considered in the calculation.
Some banks offer to absorb part or all of the refinancing costs (for example, legal fees) as an incentive to attract new borrowers, especially for large loan amounts. If such an offer exists, it can significantly change the breakeven period calculation, because the initial costs to be covered become much smaller, making refinancing more attractive even if the difference in rates between the old and new loan is not very large. Always specifically ask about such incentives when discussing with bank officers, as they are rarely advertised openly and usually need to be negotiated individually.
Most Important Point: A Low Rate Doesn't Necessarily Mean It's Worth It
This is the main message that this calculator is trying to convey: refinancing is not automatically a good decision simply because the new rate is lower than your current rate. If the refinancing costs (legal fees, stamp duty, valuation, redemption penalties) exceed the amount of interest you would save, or if the payback period is longer than the period you plan to stay in the house or with the loan, for example, if you plan to sell the house within two years, refinancing may not be worth it even though the new rate looks attractive on paper.
On the other hand, if the remaining term of your loan is still long, for example, more than 15 years, and the difference in rates between the old and new loan is quite significant, the payback period is usually much shorter compared to the remaining term of the loan, making refinancing a financially sound move in the long term.
This also means that two borrowers with the same new rate offer can come to completely different conclusions about whether to refinance, simply because of differences in the remaining loan term, the outstanding balance, or their long-term plans for the property. There is no one-size-fits-all answer, which is why individual calculations using your actual numbers are important before making a decision.
Calculation Example: RM350,000 Balance from 4.5% to 3.8%
Say your current home loan balance is RM350,000, at the current rate of 4.5% per year, with a remaining term of 20 years. Another bank offers a refinancing option at a rate of 3.8% per year, with the same term of 20 years.
From the perspective of refinancing costs, you need to take into account the legal fees for the new loan agreement, the stamp duty on the loan at a rate of 0.5% of the new loan amount (equivalent to approximately RM1,750 for a RM350,000 loan), and the property valuation fees by a licensed valuer. If your existing bank also imposes an early repayment penalty because you are leaving before a certain period, this amount is also added to the overall costs that you need to bear.
With a difference in rate of 0.7 percentage points (from 4.5% to 3.8%) on the remaining RM350,000 over 20 years, the monthly and total interest savings can be quite significant, potentially providing monthly savings in the range of hundreds of ringgit, and total interest savings reaching tens of thousands of ringgit over the loan period.
After deducting the refinancing costs (legal fees, stamp duty, valuation, and penalty if applicable) from the total interest saved, you will get the actual net savings figure. The payback period is calculated by dividing the total refinancing costs by the monthly savings, giving an estimate of how many months are needed before you truly "profit" from this refinancing decision.
Things to Check Before Refinancing
- Calculate the payback period, not just the interest rate. A lower rate with high refinancing costs can take years to fully recoup your investment.
- Ask about prepayment penalties on your existing loan before starting the refinancing process, as this can be a big, unexpected hidden cost.
- Think about your long-term plans for the property. If you plan to sell or move in the near future, a long payback period may make refinancing not worth it.
- Compare offers from several banks, because legal fees and valuation terms can vary slightly between banks, even though loan stamp duty is generally set at the same rate.
- Don't ignore the new loan term. Some refinancing offers extend the loan term to a maximum period, which can affect the total interest amount even if the monthly rate appears lower.
- Request a full breakdown of all refinancing costs in writing from the new bank before agreeing, to ensure there are no hidden costs that emerge later and affect your calculated savings.
Refinancing can be a smart financial strategy, but only when the actual numbers are carefully checked, not just comparing interest rates on paper. This calculator helps you see the full picture, savings and costs, before you sign any new agreement with a bank.
Try this calculator for free at Refinance Savings Calculator.
Note: The numbers in this article are illustrative estimates only. Actual fees, redemption penalties, and rates offered may vary according to the bank and borrower's profile. Please obtain official quotes and advice from a bank or licensed financial advisor before making a refinancing decision.




