When selling a house with a profit of RM150,000 on paper, many people immediately feel happy and start planning how to use that money. But that RM150,000 figure is just the RAW PROFIT, before deducting agent commission, disposal costs, and most importantly, the Land and Property Gain Tax (RPGT). After all these deductions, the actual amount that enters your bank account can be much smaller, sometimes surprising many sellers who have already planned their expenses based on that raw figure. The Net Property Profit Calculator at hartanahbumiputera.com calculates all of this at once, including annual return on investment (ROI), so you can see the real picture before making a decision to sell.
Why "Raw Profit" Isn't the Same as the Money You Take Home
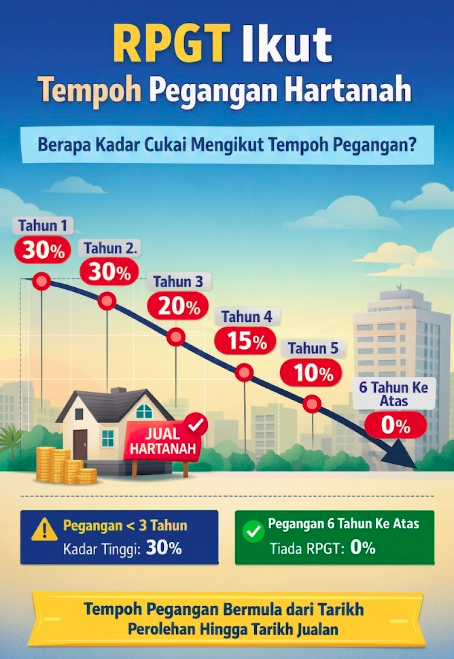
Raw profit is simply the selling price minus the original purchase price, the easiest and most frequently mentioned figure when talking about selling a house. But to arrive at the actual NET PROFIT, there are several more deductions that must be considered: acquisition costs (when you bought it earlier), disposal costs (when you sell it), real estate agent commission, and RPGT calculated based on the holding period and seller category.
This calculator also calculates ROI% (return on investment) and ROI Annualized (annualized), allowing you to fairly compare the return on this property investment with other investments such as unit trusts or shares, which are typically reported as a percentage per year.
Many first-time sellers are surprised when they realize how big the gap is between gross profit and net profit. This doesn't mean it's a bad investment property, but it reminds us of how important it is to account for all costs before making any financial plans based on property sale figures, just as you can't assume gross salary is the same as net salary after KWSP and income tax deductions.
This calculator is very useful for owners considering whether to sell now or wait, as it allows you to simulate different sale price scenarios and holding periods, see the actual impact on your pocket, before making a final decision to put the property on the market.
How Net Profit and ROI Are Calculated
The basic formula for net profit is as follows:
- Gross profit = Disposal price - Acquisition price
- Costs deducted = acquisition cost + disposal cost + agent commission (if no value is stated, the calculator assumes a default of 3% of the disposal price) + RPGT that needs to be paid
- Net profit = Gross profit - total costs deducted
RPGT here is calculated in the same way as the RPGT Calculator (rate according to holding period and seller category), but agent commission is also included as part of the disposal cost when calculating taxable profit, so the RPGT calculated here may be slightly different (usually lower) compared to if you calculate RPGT alone without considering commission.
After obtaining the net profit, two other important metrics are calculated:
- ROI% (Return on Investment) = Net profit / Amount invested (where amount invested = purchase price + purchase cost)
- Annualized ROI% = ROI% / number of years held
Annualized ROI is very useful for making "fair" comparisons, because a 20% return after 4 years is vastly different in quality compared to a 20% return after just 1 year. With this metric, you can place your property's return next to the average annual return of other investments to make a more meaningful comparison, not just compare raw ringgit figures.
Calculation Example: RM400,000 House Sold for RM550,000, With Agent Commission
Use the same example as before: house bought for RM400,000 (purchase cost RM10,000), sold for RM550,000 after 4 years (disposal cost RM15,000), but this time we add a 3% agent commission from the selling price.
- Agent commission: RM550,000 x 3% = RM16,500
- Gross profit: RM550,000 - RM400,000 = RM150,000
- Total disposal cost (original cost + commission): RM15,000 + RM16,500 = RM31,500
- Taxable gain for RPGT (taking commission into account): (RM550,000 - RM31,500) - (RM400,000 + RM10,000) = RM518,500 - RM410,000 = RM108,500
- Automatic individual exemption: whichever is higher between RM10,000 or 10% x RM108,500 = RM10,850
- Taxable gain after exemption: RM108,500 - RM10,850 = RM97,650
- RPGT (year 4 rate, individual = 20%): RM97,650 x 20% = RM19,530
- Net profit: RM150,000 - RM10,000 - RM15,000 - RM16,500 - RM19,530 = RM88,970
Now for ROI: total invested = RM400,000 + RM10,000 = RM410,000.
- ROI% = RM88,970 / RM410,000 = 21.70%
- Annual ROI (4 years) = 21.70% / 4 = approximately 5.43% per year
Note how far RM88,970 (the actual net profit) is from RM150,000 (the gross profit you might have initially assumed), a drop of more than 40%! If the seller compares this annual ROI of 5.43% with the average return of other investments, they can objectively evaluate whether this property is truly a worthwhile investment compared to other alternatives over the same 4-year period.
Interestingly, if the agent's commission is not included in the calculation (for example, the seller sells directly without an agent), the net profit will be higher since the RM16,500 cost does not exist. However, the RPGT will be slightly higher because the deductible disposal cost becomes smaller. This shows how the decision to use an agent or not also affects the tax calculation, not just the commission cost alone.
Practical Tips and Common Mistakes
- Don't negotiate the selling price based on gross profit alone. Always calculate net profit first so you know the real "minimum price" needed to achieve your financial goals.
- The 3% agent commission is just a lazy estimate. The actual rate can be negotiated with your agent, so enter the exact figure in the calculator once you have an agreement.
- Compare Annual ROI with other investments. This is the fairest way to assess whether this property is a good investment compared to fixed deposits, unit trusts, or other options.
- Consider time as well as money. Holding the property longer usually reduces the RPGT rate, but also means your capital is "tied up" in the property for a longer period.
- Recheck your old acquisition costs. Many sellers forget the actual acquisition costs from years ago; find the receipts and documents again so your net profit calculation is more accurate.
- Simulate several different sale period scenarios. Compare net profit and Annual ROI if you sell now versus waiting one or two years more, since the RPGT impact can change significantly.
- Don't forget other "hidden" costs. Costs such as pre-sale repairs, additional advertising fees, or moving costs for a new house are not included in this calculator, so account for them separately in your personal budget.
- Use the Annual ROI figure for strategic decisions, not just for satisfaction. A large net profit in ringgit doesn't necessarily mean a good Annual ROI if the holding period is very long; always evaluate both metrics together.
- Share these figures with your spouse or investment partner. If the property is jointly owned, recalculate each owner's share of net profit and ROI according to their respective ownership ratios to avoid any financial misunderstandings.
With this calculator, you can get a realistic view before making a big decision to sell your property.
Try this calculator for free at Property Net Profit Calculator.
Note: The figures above are estimates for planning purposes only and are not financial or tax advice. The RPGT rates, actual agent commissions and other costs need to be confirmed with LHDN, your real estate agent and lawyer.




