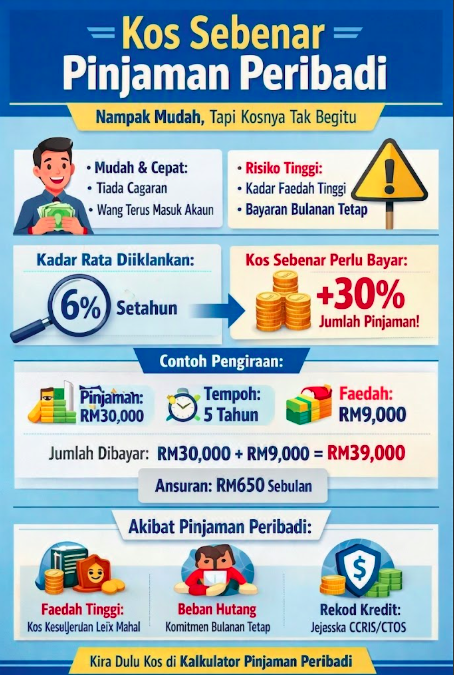
Personal loans are usually the quick choice when you need immediate cash, no collateral is required, the approval process is fast, and the money is directly deposited into your account. But this convenience comes with a cost, and many borrowers are not aware of exactly how much interest they will end up paying over the loan term. Our Personal Loan Calculator helps you see the real numbers before signing.
Personal loans differ from home loans and car loans in one fundamental aspect: they are not tied to any specific asset. You can use the money for anything, wedding costs, medical treatment, paying existing debts, or other emergencies. This flexibility is what makes personal loans popular, but it's also why lenders charge higher rates, since there is no asset that can be seized to reduce their losses if the borrower fails to pay.
Personal loan approvals also largely depend on the borrower's fixed income and credit history, since banks have no physical asset as collateral, they rely entirely on their assessment of your ability to repay based on your payslips, bank statements, and credit reports such as CCRIS/CTOS.
What makes personal loans different
Just like car loans that we discussed in a separate article, personal loans in Malaysia also use the flat rate method, not the reducing balance method used for home loans. This means that interest is calculated on the full loan amount throughout the entire term, not on the decreasing balance.
The difference with car loans is that personal loans are UNSECURED, meaning there is no collateral such as a car or house that can be repossessed by the bank if you fail to make payments. Because of this higher risk to the lender compared to secured loans, the interest rates charged are also higher. This calculator uses an illustrative average rate of 6.0% per year, with a term option between 1 to 10 years, which is much higher compared to the average rate of 2.8% for car loans.
This order of rates (from lowest to highest) actually reflects the level of risk and collateral for each type of loan: home loans (secured with property, reducing balance method, lowest rate), car loans (secured with a vehicle, average rate), and personal loans (no direct collateral, highest average rate among the three). This order is consistent throughout the financial industry, not just in our calculator, it reflects how lenders price their risk.
How loan costs are calculated
The formula is the same as for car loans:
Total interest = Loan amount x Average rate x Number of years
This total interest is spread evenly over the term, monthly payment = (loan amount + total interest) divided by the number of months. Because this average rate method is the same as discussed for car loans, the effective rate you actually experience is also higher than the quoted average rate, even though 6.0% is already high compared to secured loan rates.
The reason personal loans are only allowed for a maximum of 10 years (compared to home loans which can go up to 35 years), and the loan amount is usually smaller, monthly installments for personal loans often appear "affordable" in absolute terms, but the cost rate compared to the loan amount (in percentage) is actually much higher compared to secured loans.
Example: RM30,000 personal loan over 5 years
Say you apply for a RM30,000 personal loan at an average rate of 6.0% per year, over a period of 5 years.
Total interest = RM30,000 x 6.0% x 5 years = RM9,000
Total amount to be paid = RM30,000 + RM9,000 = RM39,000
Monthly installment = RM39,000 divided by 60 months (5 years x 12) = RM650 per month
Note that the total interest of RM9,000 is equivalent to 30% of the original loan amount of RM30,000, just for a 5-year period. This is a significant cost, and because of the flat rate method, the actual effective cost you experience is even higher than the quoted 6.0%.
As a comparison, if the period is shortened to 3 years for the same loan amount of RM30,000: total interest = RM30,000 x 6.0% x 3 years = RM5,400, total amount = RM35,400, monthly installment = RM35,400 divided by 36 months = RM983 per month. The monthly installment increases significantly compared to the 5-year period (RM650), but the total interest paid (RM5,400) is much lower than RM9,000 over 5 years, a saving of RM3,600. This shows again that a longer period not only provides lighter monthly installments, it also means a higher overall cost, a tradeoff that needs to be carefully considered according to your actual needs and financial capability.
If we compare the total interest of RM9,000 (over 5 years) with RM5,400 (over 3 years) above in terms of percentage cost compared to the original loan amount of RM30,000, we see 30% compared to 18%. This is a much higher overall cost compared to secured loans such as home loans, once again emphasizing why personal loans are most suitable to be used sparingly, for amounts that are really needed and for the shortest period that you can manage.
Practical tips: when personal loans make sense, and when they don't
- Suitable for short-term or emergency needs. Personal loans are most suitable for urgent needs such as emergency medical expenses, essential repairs, or other short-term needs where you need quick cash and are confident you can repay within a short period.
- Avoid using for mortgage down payments. This is an important mistake to avoid. Considering the effective cost of a personal loan is much higher compared to other housing-specific financing options (such as LPPSA for public servants, or standard home loans), using a personal loan to accumulate a mortgage down payment will burden you with two financing costs at the same time, one for the personal loan and another for the home loan itself.
- Compare rates from several banks/institutions. Average personal loan rates can vary significantly between banks and non-bank financial institutions, compare several before choosing.
- Understand the fixed interest amount even if you pay early. Some average-rate personal loans do not offer a "full interest rebate" if you settle early, carefully check these terms.
- Calculate first, don't just look at monthly instalments. Monthly instalments that look "affordable" can hide a large total cost, always check the total interest amount before signing.
- Avoid using one personal loan to pay off another personal loan. This cycle (sometimes called "dig a hole, fill a hole") can quickly lead to unmanageable debt, because each new loan brings additional interest costs of its own.
- Understand the impact on your CCRIS/CTOS. Personal loans, like other debt commitments, are recorded in your credit report and will be considered if you apply for other financing later (such as a home loan), ensure that instalment payments are always made on time to avoid negative effects on your credit record.
- Compare with alternatives such as credit cards for small amounts. For very small and very short-term needs, a credit card with a grace period may be cheaper than applying for a full personal loan, but this is only worthwhile if you are confident you can settle before the grace period ends.
Try this calculator for free at Personal Loan Calculator.
Note: The rates and figures in this calculator are illustrative estimates based on average rates, not official loan offers. The actual rate will be determined by the bank or financial institution based on your credit profile.




