When you buy a house with a bank loan, you actually need to appoint a lawyer for TWO separate matters: preparing the Sales and Purchase Agreement (SPA) and preparing the Loan Agreement with the bank. Many buyers are unaware of these two separate bills until the demand letter for fees arrives, and some are surprised because they assumed a single payment would be sufficient for both documents. The Legal Fee Calculator on hartanahbumiputera.com is specially designed to clarify this confusion, so you know early on how much actual legal fees you need to prepare before proceeding with the purchase, and can discuss more confidently when meeting with your lawyer.
Why There Are Two Legal Fees, Not One
The SPA is a contract between you and the property seller, while the Loan Agreement is a contract between you and the bank financing the purchase. Both need to be properly prepared by a licensed lawyer, and each is charged according to the same scale but used separately, once on the property price (for the SPA) and once again on the loan amount (for the Loan Agreement). If you buy in full cash without a bank loan, you only need to pay the SPA fee. However, most buyers in Malaysia finance at least part of their purchase, so both these fees usually apply simultaneously.
Some buyers wonder why these two matters aren't combined into a single bill.
The reason is, legally, the SPA and the Loan Agreement are two separate contracts involving different parties (the seller on one side, the bank on the other), so the legal work involved, checks, document preparation, and registration are also separate. In fact, some buyers choose to appoint two different law firms, one specifically for the SPA and another for the Loan Agreement, although this is less common than appointing the same firm for both to facilitate coordination.
From a time perspective, usually both lawyers (or the same firm handling both roles) will work more or less simultaneously, since the bank loan is usually dependent on the progress of the SPA. This means you need to prepare both fees within a more or less similar timeframe, not several months apart, so plan your cash flow by taking both into account simultaneously, not one after the other.
Official Scale and Why the Actual Bill is Higher
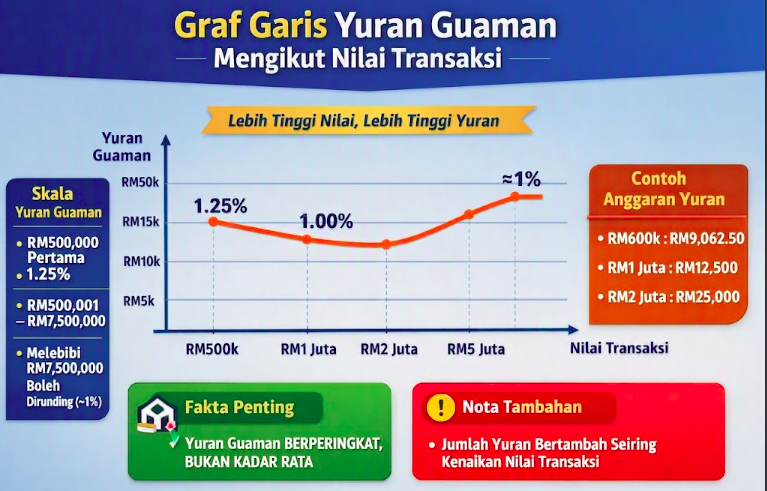
Legal fees are regulated under the Solicitors Remuneration Order (Amendment) 2023. The tiered scale is as follows:
| Transaction Value | Statutory Rate |
|---|---|
| First RM500,000 | 1.25% (minimum fee RM500) |
| Balance up to RM7,500,000 | 1.00% |
| Exceeding RM7,500,000 | Negotiable (usually around 1%) |
This is a STATUTORI scale, i.e. the minimum rate allowed under the law. In practice, real law firms in Malaysia rarely charge exactly at this minimum rate. The calculator on this page adds a 25% markup over the statutory rate, based on cross-checking with a fee calculator published by three separate law firms, hence it more accurately reflects what you will BE CHARGED in real life, not just the minimum rate which is rarely used. Therefore, consider the calculator's number as a realistic estimate of "what you might pay", while the statutory rate without markup is the "minimum limit under the law".
Why do law firms charge higher than the minimum? Some of the reasons include the firm's operational costs, the complexity of certain transactions (for example, if the property has title issues or requires additional searches), and market demand in certain areas. Although the law sets a minimum rate to protect users from unreasonable excessive charges, it does not prevent firms from charging higher amounts as long as both parties agree.
This does not mean all firms charge the same with a 25% markup. Some larger firms or those in main urban areas may charge even higher, while smaller firms or those in less competitive areas may be closer to the statutory rate. Therefore, this calculator's number should be used as a planning estimate, not as a final quote, and you are encouraged to obtain at least two or three quotes before making a decision.
Calculation Example: RM600,000 House with a RM480,000 Loan
Let's calculate both fees separately.
SPA Legal Fees (on house price RM600,000):
- First RM500,000 x 1.25% = RM6,250
- Remaining RM100,000 (600,000 - 500,000) x 1.00% = RM1,000
- Total statutory rate = RM7,250
- With 25% markup: RM7,250 x 1.25 = RM9,062.50
Loan Agreement Legal Fees (on loan amount RM480,000):
- Since RM480,000 is in the first bracket (below RM500,000): RM480,000 x 1.25% = RM6,000
- With 25% markup: RM6,000 x 1.25 = RM7,500
The total legal fees required are RM9,062.50 + RM7,500 = RM16,562.50. Comparing this with the statutory rate without markup which is only RM13,250 (RM7,250 + RM6,000), you can see a difference of more than RM3,000 between the "minimum on-paper rate" and what is usually actually charged. If this buyer only budgets based on the statutory rate alone, they may face a cash shortfall of RM3,312.50 when the actual bill arrives.
Frequently Asked Questions About Legal Fees
Can I negotiate legal fees with a lawyer? Yes, especially for high-value transactions. Many firms are willing to offer a slight discount below the standard market rate to attract more customers.
Are legal fees inclusive of other costs such as stamps and searches? No. Legal service fees are usually separate from disbursements such as document stamping costs and land title searches, which are charged separately.
If I buy in cash without a loan, do I still need to pay two fees? No, you only need to pay the SPA legal fee since there is no loan agreement to be prepared.
Is the legal fee the same for new property from a developer and subsale property? The calculation scale is basically the same, but new property from a developer sometimes has special negotiations or promotional packages that can reduce this fee, so always ask during the booking process.
Practical Tips and Common Mistakes
- Always ask for a written quote from the lawyer before hiring. Some firms are willing to negotiate below market rates, especially for high-value transactions.
- Don't forget that legal fees may have ADDITIONAL costs. In addition to service charges, there are usually various payments (disbursements) such as stamp duty and searches, which are not included in the calculation above.
- You can use the same lawyer for the SPA and Loan Agreement. This sometimes simplifies the process and reduces the risk of delays in coordination between two different firms.
- Check if the fees can be included in the loan. Some bank packages allow legal fees to be financed at once, reducing the need for cash upfront, although this means you will pay interest on it in the long run.
- Read the draft SPA and Loan Agreement carefully before signing. The legal fees you pay are for the professional service of the lawyer, so use this opportunity to ask questions and understand each important clause.
- Ask early how long the process will take. The preparation time for the SPA and Loan Agreement varies according to the complexity of the transaction and the workload of the firm, so this helps you plan the handover date more realistically.
By understanding these two components of the fees separately, you can negotiate with more confidence and avoid being surprised when the bill arrives.
Try this calculator for free at Legal Fee Calculator.
Note: The figures above are estimates for planning purposes only. The actual fees may vary according to the law firm and transaction complexity; please obtain an official quotation from your licensed lawyer.




