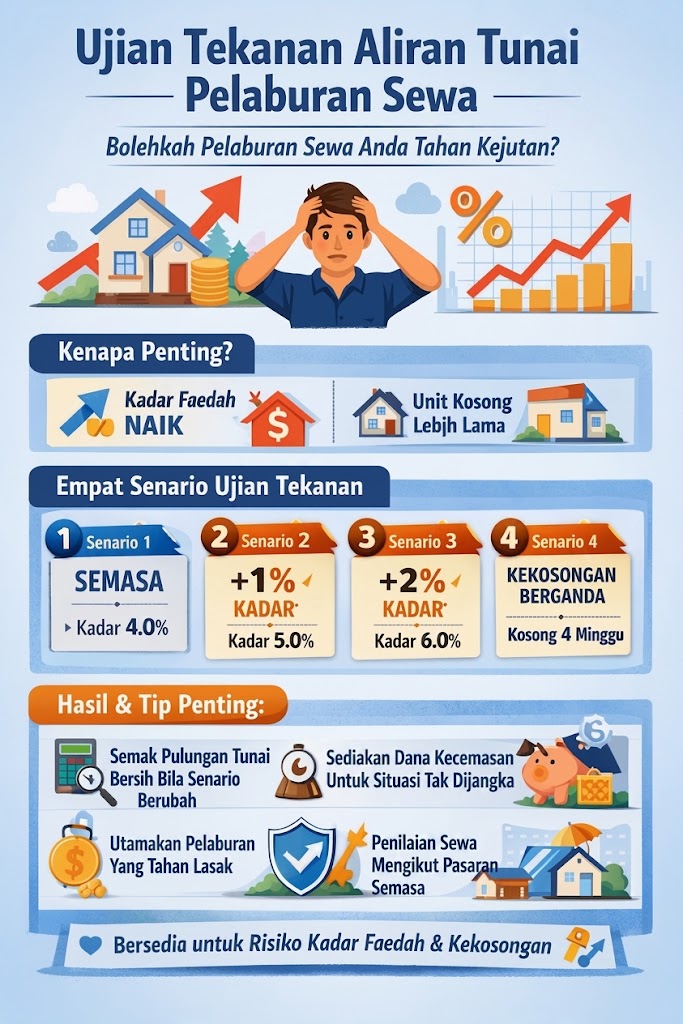
Most property investors calculate Cash-on-Cash Return (CoCR) only once, on the day they are considering buying, using the current interest rate. After that, they assume that number remains forever. In reality, interest rates fluctuate according to economic cycles, and tenants can move at any time, leaving the unit vacant longer than expected. The Investment Risk & Cash Flow Calculator on this page is specifically designed to reveal how fragile (or strong) your rental investment is when conditions change.
Why This Stress Test Is Important
Imagine buying a rental property with a CoCR that looks healthy, say 8%, at the current interest rate. That number seems attractive, so you proceed with the purchase. But two years later, Bank Negara Malaysia increases the OPR, your bank raises loan rates, and suddenly your monthly payments increase significantly. At the same time, your existing tenant moves out and the unit remains vacant for two months before a new tenant is found. Suddenly, the 8% CoCR you calculated earlier is no longer relevant, and an investment that looked profitable is now a monthly burden.
This is why this calculator is important, it doesn't just calculate CoCR once, but performs calculations that
SAME across four different scenarios, so you can clearly see how much "breathing room" (safety margin) your investment actually has before it becomes negative.
This is particularly relevant in Malaysia, where most home loans use floating rates tied to Bank Negara Malaysia's OPR. Over the 25 to 35-year loan period, it is reasonable to expect OPR to rise and fall several times according to economic cycles. A savvy investor plans for this possibility from the start, rather than being surprised when it happens several years after purchasing.
Four Scenarios Tested
This calculator takes the same basic inputs as the CoCR calculation (property price, loan amount, monthly rent, annual expenses, base interest rate), then recalculates the monthly payment and resulting CoCR in the following four scenarios:
- Scenario 1, Current: current interest rate and normal vacancy assumption (default 2 weeks per year).
- Scenario 2, Interest Rate +1 Percentage Point: monthly payment recalculated with an interest rate 1 percentage point higher than current, vacancy remains normal.
- Scenario 3, Interest Rate +2 Percentage Points: monthly payment recalculated with an interest rate 2 percentage points higher than current, vacancy remains normal.
- Scenario 4, Double Vacancy: interest rate remains current, but the vacancy assumption is doubled from 2 weeks to 4 weeks per year, simulating a longer-than-expected period to find a new tenant.
Each scenario produces a different CoCR, allowing you to clearly see which factor most affects your returns, interest rate increases, or vacancy risk.
This calculator essentially performs the same CoCR calculation as in the Cash-on-Cash Return calculator, only repeated four times with different input interest rates and vacancy rates each time. This means you don't need to learn a new concept, just need to understand how to read and compare the four adjacent results.
Calculation Example: Loan RM450,000, Rent RM2,200
Say you have a property with a loan of RM450,000, monthly rent of RM2,200, annual expenses of RM4,000, and a base interest rate of 4.0%, with an assumed vacancy of 2 weeks per year.
Scenario 1 (Current, 4.0%): at this rate, the monthly payment is at the base level, and the resulting CoCR represents the starting point (baseline) for comparison.
Scenario 2 (+1%, so 5.0%): the monthly payment increases significantly due to the higher interest rate. Because this increase in payment continues to reduce the annual net cash flow (which is the numerator in the CoCR formula), the CoCR will FALL compared to Scenario 1, sometimes significantly if the original margin is already thin.
Scenario 3 (+2%, so 6.0%): the monthly payment increases even more, and the CoCR will fall EVEN FURTHER compared to Scenario 2. If the original CoCR in Scenario 1 is already low (for example, below 3-4%), this scenario is likely to push the CoCR into negative territory, meaning the property starts "eating" your money every month at the higher interest rate.
Scenario 4 (4 weeks vacancy): in this scenario, the interest rate remains at 4.0%, but the rental income effectively decreases because the unit is vacant for a longer period (4 weeks compared to 2 weeks per year). This also reduces the CoCR compared to scenario 1, although the reason differs from the increase in interest rates; it is due to lost rental income, not increased financing costs.
By comparing these four scenarios side by side, you can assess whether this investment remains "safe" (positive CoCR) even in the worst conditions, or if it is only profitable under ideal conditions at present.
Some investors find that their properties remain positive in scenario 2 (+1%) but fall into negative territory in scenario 3 (+2%). This provides useful information: the investment can withstand moderate interest rate increases, but is not strong enough to handle larger increases. This information helps you decide whether to keep more emergency funds, reduce the loan amount (with a larger down payment), or look for other properties with a higher original CoCR margin.
Practical Tip Using Stress Test Results
- If your CoCR drops into negative with just a +1% increase in interest rate, this is a serious warning sign. This means your investment's safety margin is too thin to withstand any interest rate shocks, which occur regularly in normal economic cycles.
- Set aside a dedicated emergency fund (buffer) specifically for your investment property, enough to cover several months of payments if interest rates rise or vacancies last longer than expected.
- Don't just calculate once and forget. Repeat this stress test every time OPR changes or when the fixed-rate loan period (if any) ends, to ensure your investment remains solid under current conditions.
- Use the results of scenario 4 (double vacancies) to assess location quality. Areas with high rental demand and quick tenant turnover are less risky in this scenario compared to locations with weak rental demand or oversupply of units.
- Compare several candidate properties using the same stress test. Two properties might have similar original CoCR in scenario 1, but differ greatly in resilience in scenarios 2 to 4. Properties that are more "durable" across all four scenarios are usually safer long-term choices, even if their original CoCR is slightly lower.
- Avoid loan types with interest rates too sensitive to OPR changes without any caps. If a bank offers semi-fixed or interest rate-capped options, this can reduce some of the risks exposed in scenarios 2 and 3 in this calculator, even though it might come with a higher margin initially.
- Run this stress test again every time you consider a new investment property. Don't rely solely on past experience, each property has a unique combination of price, rent, and loan, so its safety margin needs to be assessed separately each time.
Try this calculator for free at Investment Risk & Cash Flow Calculator.
Note: All numbers in this article are illustrative estimates for planning purposes only, not financial or investment advice. Changes in interest rates and actual vacancy risks cannot be predicted with certainty, please plan sufficient safety margins before investing.




