Full-Flexi or Semi-Flexi home loans are often promoted as a "smart" way to reduce loan interest, but they also bring additional costs compared to regular fixed-rate loans. The Full-Flexi vs Semi-Flexi calculator on HartanahBumiputera helps you calculate whether this facility is really worth it for your financial lifestyle, or just an unnecessary additional charge for most borrowers.
How the Flexi Facility Works
Full-Flexi and Semi-Flexi loans are linked to a related account, where any surplus cash you save in it will "offset" your loan balance for the purpose of interest calculation. This means, even though technically the money still belongs to you and can be withdrawn anytime, it is calculated as if it reduces your loan balance at the time interest is calculated, thereby reducing the amount of interest charged for that month.
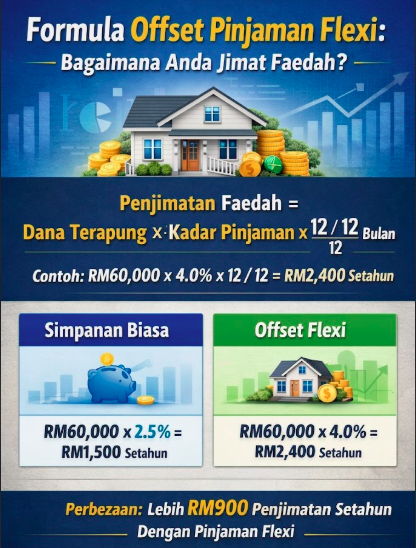
This calculator compares the actual value of this offset facility, compared to if the same surplus money was simply saved in a regular savings account, which only provides returns at a savings interest rate (default illustration 2.5% per year), much lower than the home loan rate (usually around 4% per year).
This concept can be confusing at first because the money isn't "lost" or "invested" anywhere; it simply stays in the account linked to your loan, but it directly affects how the loan interest is calculated each month. This is entirely different from a standard term loan, where your savings and the outstanding balance of your loan are completely separate, with no interaction between them in terms of interest calculation.
It should be noted that "Full-Flexi" and "Semi-Flexi" are not uniform terms across the banking industry; each bank may have its own variations in how this offset facility operates, minimum balance limits, and methods of accessing funds. Therefore, in addition to using this calculator to assess the overall value of the flexi facility, make sure you also carefully read the specific product terms and conditions offered by your chosen bank, including any additional monthly statement charges or administrative fees that may be imposed for this facility throughout the loan period.
Why Offset on Loan Rates is More Valuable
The logic behind this flexi facility is simple: every ringgit that offsets your loan balance "saves" you interest at the loan rate (for example, 4%), compared to if the same ringgit only "earns" interest at the savings rate (for example, 2.5%). The difference between these two rates is the actual value you gain from choosing the flexi facility compared to keeping your money in a regular savings account.
However, this flexi feature usually also comes with a small premium interest rate compared to a standard term loan without the flexi feature, as a trade-off for this additional flexibility. Therefore, to determine whether this flexi feature is worth it, you need to compare the interest savings from the offset with the cost of the premium rate you pay to get this facility throughout the loan period.
Who benefits the most from this facility? Those who consistently hold a significant amount of excess cash, such as business owners with fluctuating cash flow (who need large savings for business emergencies), or disciplined savers with large savings that are not immediately needed. For these groups, offsetting against the standard loan rate is usually far more valuable than the standard savings rate. Conversely, those who rarely have significant excess cash will gain little benefit from this facility, and may be better off choosing a simpler standard term loan without the ongoing additional premium rate.
There is also a middle group, namely permanent salary earners who have a small surplus at the end of each month, but inconsistently from month to month. For this group, the decision depends on how large the premium rate is compared to the realistic average of floating funds they can maintain throughout the year. This calculator helps this middle group test various floating fund scenarios, so they can see at what level the flexi facility starts to provide meaningful value compared to its additional cost.
Example Calculation: RM60,000 Floating Funds Over 5 Years
Say you on average hold RM60,000 in cash surplus in your flexi loan related account throughout the five-year period. Your home loan rate is 4.0% per year, compared to a normal savings rate of 2.5% per year.
If this RM60,000 is used to offset the loan balance at 4.0%, it illustratively saves interest within the range of RM2,400 per year (4.0% of RM60,000), or approximately RM12,000 over the five-year period, assuming the floating funds remain fairly consistent throughout that period. Compare this with if the same RM60,000 is only saved in a normal savings account at 2.5%, it only earns interest within the range of RM1,500 per year, or approximately RM7,500 over five years. The difference between these two scenarios, approximately RM4,500 over five years in this illustrative example, is the additional value gained from choosing the offset facility compared to normal savings.
However, if this flexi facility brings an additional rate premium, say 0.1 to 0.2 percentage points higher than a normal term loan, charged on the entire loan balance (not just the RM60,000 floating funds), this premium cost could become quite significant if your loan balance is large. This calculator helps you compare the savings from offset, compared to the premium cost paid for the entire loan balance, so you can see whether it is truly worthwhile for your own financial profile.
Tips Before Choosing Flexi Facility
- Honest with yourself about your financial habits. If you rarely have a significant savings balance at the end of the month, flexi facilities may not provide much benefit to you.
- Check the premium rate charged for the flexi facility compared to a regular loan from the same bank, and compare it with the potential savings from offsetting throughout the loan term.
- Business owners and irregularly paid employees usually benefit more, as they need to keep a large cash reserve for emergencies, and this reserve can offset the loan balance all at once.
- Understand the withdrawal limits and how to access funds in your flexi account, as each bank has different rules about how and when you can withdraw money that has "offset" the loan.
- Don't choose flexi just because it sounds more advanced. If you won't keep a significant cash balance, a simpler regular loan without a premium may be more cost-effective overall for you.
- Reassess your options when your financial situation changes, for example, when you start your own business or income becomes more unpredictable, because at that time the value of the offset facility may increase compared to when you initially applied for the loan.
Full-Flexi or Semi-Flexi facilities are not suitable for everyone; they are most valuable for those who consistently hold large surplus funds. Use this calculator to test your own scenarios, based on realistic floating funds for your financial situation.
Try this calculator for free at Full-Flexi vs Semi-Flexi Calculator.
Note: This calculation is an illustrative estimate based on the assumption of consistent floating funds. Actual rates, flexi premiums, and product structures may vary according to the bank. Please refer to the official product terms and licensed financial advisors before making a decision.




