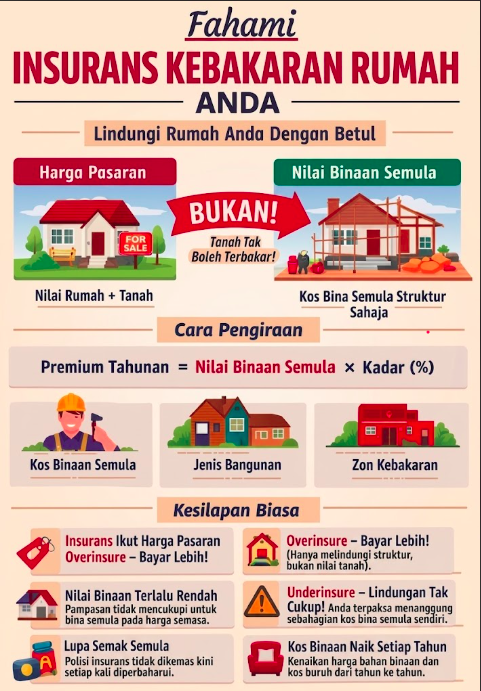
Many first-time homebuyers mistakenly assume that fire insurance is calculated based on the selling price of their homes. When the quoted premium appears "low" compared to the million-ringgit house price, many just agree without question, or alternatively, worry it's too cheap to protect their "million-ringgit" asset. In reality, fire insurance is calculated based on a completely different basis from your property's market value, and this misunderstanding can cause you to overinsure (pay more than necessary) or underinsure (have insufficient coverage). Our Fire Insurance Calculator helps you calculate the correct figure.
What fire insurance actually protects
In Malaysia, fire insurance is MANDATORY for any property that still has an outstanding bank loan. The bank will require you to take out this policy as part of the loan agreement, usually with the bank named as the "primary beneficiary" of the policy until the loan is fully settled. However, what many are not aware of is that fire insurance premiums are calculated based on the REBUILD VALUE (reconstruction value) of the physical structure of the house, NOT the market value or selling price of the property.
This is because land cannot burn. If your house is destroyed by fire, the land underneath still remains and still has value; only the building structure (walls, roof, floor, etc.) is lost. Therefore, what the insurance needs to pay back is the cost to REBUILD that structure from scratch, not the overall value of the property including the land. This is why two houses with the same market price can have very different fire insurance premiums, depending on how large the land component is compared to the building structure in that price.
This principle applies whether it is for landed houses (terraced, semi-D, bungalow) or strata units (condominiums, apartments). For landed houses, the owner usually takes out a fire insurance policy themselves for their unit's structure. For strata units, the management body (JMB or MC) usually takes out a comprehensive fire insurance policy for the entire building, and this cost is shared among the unit owners through maintenance fees or special charges, although some banks may still require strata unit owners to have additional coverage in their own name as a loan condition.
How the premium is actually calculated
The basic formula is simple:
Annual Premium = Rebuild Value x Percentage Rate
This calculator uses an illustrative default rate of 0.105% per year as a common starting point. However, it's important to note that the actual rate varies according to the insurance company, type of construction (for example, brick houses versus wooden houses), and fire risk zones based on location (commercial areas may have higher risk compared to open residential areas). Therefore, this 0.105% rate is a general estimate to provide a rough idea, not a fixed rate applicable to all policies.
The most important thing to understand: the correct input for this calculator is an estimate of the REPAIR COST of the structure, not the selling price or market value of your property. If you are unsure about the rebuild cost of your house, you can get an estimate from an engineer, architect, or sometimes banks/appraisers will include this estimate during the loan process.
The easiest way to estimate the rebuild value yourself (as a starting point before getting professional advice) is to multiply the floor area of the structure (not the land area) by the typical construction cost per square foot according to the type of construction in your area. Some housing developers also state the original construction cost of the unit in the sale documents, which can be a useful reference point, although the actual rebuild cost today may be higher due to increased construction material prices and labor costs since the unit was first built. Some owners also choose to get an estimate from a quantity surveyor for a more accurate figure, especially for larger homes or homes with complex designs.
Other factors that also influence the actual rate (not just this illustrative 0.105% lapse rate) include the type of structural building material (reinforced concrete houses are usually considered lower risk compared to wooden structures), surrounding area density, distance to the nearest fire station, and the history of fire claims in the area. This is why two houses with the same rebuild value but in different locations may be charged slightly different percentage rates by the same insurance company.
Example: a terrace house valued at RM600,000
Say you have a terrace house with a market value of RM600,000. This price includes the value of the land AND the building structure. After getting an estimate, say the cost to rebuild the house structure from scratch (excluding land value) is estimated at RM280,000 only, which is much lower than the full market price.
If we use the default rate of 0.105%, the annual premium calculation would be:
RM280,000 x 0.105% = RM294 per year
Now compare that to if someone mistakenly uses the full market price of RM600,000 as the calculation basis:
RM600,000 x 0.105% = RM630 per year
See the difference, more than double! If you use the RM600,000 market price as the insurance basis, you are actually over-insuring your house structure (protecting more than what is actually needed to rebuild), and ultimately paying much higher premiums each year without any additional benefits, because when a claim is made, the compensation payment is always based on the actual rebuild cost, not the inflated coverage amount.
The RM336 difference per year (RM630 minus RM294) may seem small in one year, but when multiplied by a 30-year loan term, it amounts to more than RM10,000 paid unnecessarily throughout the loan period, simply because of an incorrect initial calculation basis. This shows why a simple step, namely correcting the basic input (reconstruction value, not market price), can have a significant financial impact in the long term.
Practical tips and common mistakes
- Separate the land value from the structure value. This is the most common mistake. Always ask, "what would it cost to rebuild this house from scratch?" not "how much would this house be worth if it were sold?"
- Don't overinsure accidentally. Overinsuring doesn't mean you get more compensation if there's a fire, insurance companies only pay based on the actual rebuild cost, so any extra premium paid is just a waste.
- Don't underinsure either. Conversely, if you estimate the rebuild value too low, you might not be adequately protected when a real claim is needed, and some policies have an "average" clause that reduces compensation proportionally if underinsurance is found.
- Review the rebuild value periodically. Construction costs (materials, labour) increase year by year, so a reasonable rebuild value from 10 years ago may no longer be sufficient today.
- Understand the difference from home contents insurance. Fire insurance only protects the building structure, furnishings and household items usually require a separate policy.
- For strata units, check existing coverage first. Before taking out an additional policy yourself, ask the building management what is already covered under the building's comprehensive policy, so you don't pay twice for the same coverage.
- Review again when making major renovations. If you add a room, upgrade the structure, or make major modifications, the rebuild value also changes, inform your insurer so the policy remains sufficient.
Try this calculator for free at Fire Insurance Calculator.
Note: The rates and figures in this calculator are illustrative estimates for initial guidance purposes only, not official quotes from any insurance company. The actual premium must be confirmed with your insurance company or licensed agent based on a full property assessment.




