Annual bonuses, CPF withdrawals, or inheritances sometimes give you a lump sum of money suddenly. One common question is, should this money be used to pay off a large portion or the entire remaining balance of your home loan? The Early Repayment Calculator on HartanahBumiputera helps you answer this question with real numbers, by showing the impact of making a lump sum payment (once only) on your remaining loan balance.
What's the Difference Between This Calculator and the Interest Saving Calculator
This calculator differs from the Interest Saving Calculator, which calculates the effect of an additional fixed monthly payment. Here, you enter a lump sum amount paid once only in the first month, immediately reducing your remaining loan principal at that time. This calculator then calculates how many months the loan term is shortened, and how much total interest is saved, compared to continuing with the original payment schedule without the lump sum payment.
If the lump sum amount you enter is large enough to fully settle the entire remaining loan balance at once, this calculator will clearly state that your loan has been fully completed, and will not calculate any further period or interest since it is no longer relevant.
Many borrowers receive lump sums from time to time throughout the life of their housing loan, whether from consistent annual bonuses, sales commissions, or withdrawals from KWSP Account 2 for specific purposes. Without tools like this calculator, it is difficult for someone to assess whether it is better to save the money, invest it elsewhere, or channel it directly into the remaining balance of the housing loan, as these three options have very different long-term financial impacts on each other.
Many also do not realize that this decision does not have to be made as an "all or nothing" choice. You can choose to channel only a portion of the lump sum into the housing loan, while keeping the rest as emergency funds or for more pressing needs, and this calculator can be used repeatedly to test various combinations of amounts until you find the balance that is most suitable for your own financial situation and level of comfort with risk and liquidity.
When Lump Sums Are Suitable to Be Used This Way
This lump sum approach is most suitable when you receive unexpected or non-recurring extra funds, such as a large annual bonus, a KWSP withdrawal for a specific purpose, proceeds from asset sales, or an inheritance. If you do not have other more pressing financial needs (such as insufficient emergency funds, or higher interest rate debts like credit card debts), channeling this lump sum into the remaining balance of your housing loan can provide significant interest savings.
Alternatively, if you do not have a large lump sum of money but are able to set aside a little more each month consistently from your fixed income, the Interest Savings Calculator (monthly additional payment) approach may be more suitable for your situation, as it does not require you to pay out a large amount of money all at once and can be adjusted at any time according to your financial situation.
One important thing to check before making an early decision: some banks impose early repayment penalties or redemption penalties if the loan is settled within the first few years of the loan term. This calculator does not specifically model such penalties, so please check your loan agreement or contact your bank first. If you want to see the impact of redemption penalties in more detail, especially in the context of refinancing the loan to another bank, the Refinancing Savings Calculator on this page also specifically models the cost of such redemption penalties.
Another factor to consider is the opportunity cost. If your lump sum can be invested elsewhere at a higher rate of return than the interest rate on your home loan, theoretically it may be more beneficial to invest rather than pay off the loan early. However, such investments usually carry higher risks compared to the "guaranteed returns" of avoiding home loan interest, so many opt for a more conservative approach, paying off part of the remaining loan balance, especially if they are uncomfortable with the ups and downs of the investment market and prioritize long-term peace of mind over uncertain and somewhat risky additional returns.
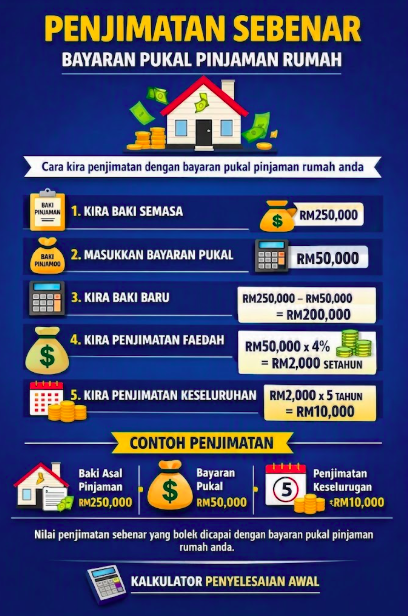
Calculation Example: RM250,000 Balance with RM50,000 Lump Sum
Suppose your outstanding home loan balance is RM250,000, at an interest rate of 4.0% per year, with 15 years remaining on the loan term. You receive a RM50,000 lump sum from your EPF withdrawal and decide to apply it directly to your outstanding loan balance this month.
With this lump sum payment, your outstanding loan balance is immediately reduced from RM250,000 to RM200,000.
Since the monthly interest going forward is calculated on this lower balance, and the monthly installments to be paid remain based on the original schedule, a larger portion of each installment will go toward reducing the principal balance compared to before. As an illustration, this action could shorten your loan term by several years from the original 15-year remaining term, and save you a total amount of interest in the range of tens of thousands of ringgit, depending on the interest rate structure and remaining term after that.
If instead you have a lump sum of RM250,000 or more, which is equal to or exceeds the remaining loan balance, the calculator will show that your loan can be fully settled at that time, and you will no longer need to make any monthly payments afterwards, subject to your bank's full settlement procedures and any required documentation.
Factors to Consider Before Making a Decision
- Check for early repayment penalties in your loan agreement. Most banks in Malaysia impose this penalty only during a specific period (for example, the first three to five years), after which it is usually no longer charged.
- Make sure your emergency fund is sufficient first. Do not use your entire emergency savings to repay the loan, as money already transferred to the house is difficult to retrieve quickly when needed.
- Compare with other debts that have higher interest rates. If you have a credit card balance or a personal loan with a higher interest rate than your home loan, it is usually more worthwhile to settle the higher interest debt first.
- Consider liquidity. Once a lump sum is transferred to your loan balance, it is no longer easily accessible compared to if it remained in a savings or more liquid investment account.
- Consider combining both strategies, that is, using part of the lump sum for early repayment, while continuing to set aside a little more each month for ongoing interest savings.
- Do not rush to make a decision as soon as the lump sum is received. Take time to compare several options using this calculator and the Interest Savings Calculator, so that you are truly confident in the approach chosen before transferring the money.
The decision to use a lump sum of money to settle a home loan earlier depends on your personal financial priorities, not just the amount of interest savings alone. Use this calculator to see the actual magnitude of the savings, so that your decision is based on facts, not assumptions alone.
Try this calculator for free at Early Settlement Calculator.
Note: This calculation is an illustrative estimate only and does not take into account early settlement penalties, administrative fees, or your bank's specific terms. Please refer to your official loan agreement and seek advice from your bank or a licensed financial advisor before making a decision.




