Many people pay their credit card bills every month, but the balance still doesn't seem to decrease. If this sounds like your situation, it's likely that the amount you're paying every month is just enough to cover the interest, not reducing the principal balance. The Credit Card Repayment Calculator on HartanahBumiputera is specially designed to show you with actual numbers how long it will take for your credit card balance to be fully paid off, and how much interest you will end up paying during that period, based on the fixed amount you're committed to paying every month.
What This Calculator Actually Measures
This calculator takes three basic inputs: your current credit card balance, the annual interest rate (APR) charged by the bank, and the fixed amount you intend to pay every month until the balance is fully paid. From there, it calculates two important figures: how many months are needed to fully repay the balance, and the total amount of interest you will pay during that period.
This is important because credit card statements usually only show the "minimum payment" each month, without showing the long-term impact if you only pay that minimum amount. By seeing the actual numbers, you can make more informed decisions, whether to increase your monthly payments, or find other ways to settle the debt faster. Many people are surprised to see how long it actually takes to fully pay off their credit card balance, even though they feel they've been paying consistently every month.
This is not just theory. According to the usual pattern of credit card users, many pay an amount that seems "reasonable" every month without checking whether that amount is actually sufficient to significantly reduce the principal balance. Without a tool like this calculator, it is difficult for someone to realize that their payments are actually just "circling" around the interest, making no real progress toward debt freedom, even if they have never missed a payment in years.
How This Calculation Works
By default, this calculator uses an illustrative APR of 18% per year, which is the typical rate for credit cards in Malaysia, but you can change it to your card's actual rate. Every month, interest is calculated on the outstanding balance, then the fixed payment you enter will first cover the interest for that month, and any remaining amount will only reduce the principal balance.
This is where the most important thing you need to understand comes in: if your fixed monthly payment is less than, or equal to, the amount of interest charged for that month, your credit card balance will not decrease at all, no matter how long you continue to pay. This calculator will clearly warn you when this situation occurs. This is called the "minimum payment trap," a situation where the borrower remains in debt indefinitely because the payments made are never enough to touch the principal balance, even though they have never appeared late or failed to make a payment.
The higher the balance and the interest rate, the higher the monthly interest amount that needs to be covered first before any payment can affect the principal balance. This means two people with the same credit card balance can be in very different situations, simply because of the difference in the monthly fixed payment amount they are committed to.
Actual Calculation Example
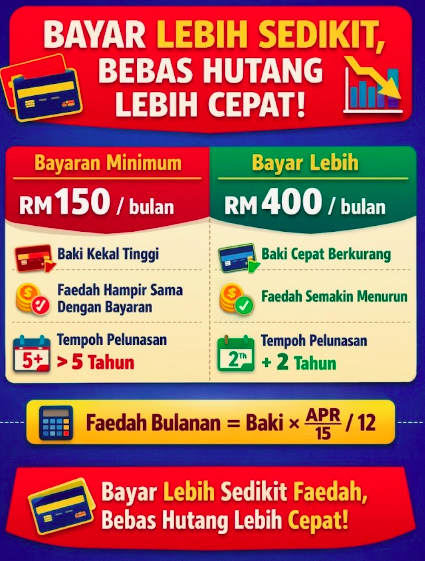
Let's use concrete numbers. Suppose your credit card balance is RM8,000, with an APR of 18% per year, and you are committed to pay RM400 per month consistently until the balance is cleared.
In the first month, the interest charged on the RM8,000 balance with a rate of 18% per year (equivalent to approximately 1.5% per month) is around RM120. Since your RM400 payment far exceeds the monthly interest, approximately RM280 of that payment directly reduces the principal balance. This process repeats every month, with the amount of interest charged gradually decreasing as the principal balance reduces, and the portion of the payment going toward the principal balance increasing. With a consistent monthly payment of RM400, the RM8,000 balance
will be cleared in approximately two years, with the total interest paid being significantly less than the original balance, due to the relatively short repayment period.
Now compare this with a situation where you can only afford to pay RM150 per month on the same balance and rate. The first month's interest on the RM8,000 balance is approximately RM120, so the RM150 payment only leaves approximately RM30 to reduce the principal balance, a very small amount compared to the total balance.
This means that the repayment process will take much longer, and the total amount of interest paid will be significantly higher compared to the previous example of RM400 per month, because the remaining principal will take years longer to decrease significantly. In fact, if the monthly payment drops to a level almost the same or lower than the monthly interest, the remaining balance could remain static for a while, without any significant reduction, even if you continue making payments every month without defaulting.
The difference between these two scenarios, RM400 per month versus RM150 per month, clearly shows why the amount of your monthly payment is the most important factor in determining how quickly you can be free from credit card debt, far more important than simply paying consistently every month regardless of the amount. Two people who are both "diligent" in paying every month could end up in very different financial positions after two or three years, simply because of the difference in the fixed amount they chose to pay initially.
Practical Tips and Common Mistakes
- Don't just pay the minimum amount stated on the statement. Banks usually set the minimum payment at a very low level so that it barely reduces the principal balance, as this benefits the bank in the long term in terms of interest.
- Use this calculator every time the interest rate or balance changes. If you make a new purchase on the same card, the balance will increase and the repayment period calculation needs to be recalculated from the beginning.
- Set a fixed payment higher than the monthly interest by a comfortable margin, not just slightly higher, so that the repayment process occurs within a reasonable timeframe and not over many years.
- Avoid adding new expenses on the card you are trying to repay. Every new expense increases the balance and prolongs the repayment period you have planned.
- If you have more than one credit card, consider focusing additional payments on the card with the highest interest rate first, while continuing to pay the minimum payments on the other cards.
- If you have extra money from a bonus or other sources, use it to reduce your credit card balance before considering other investments, as credit card interest rates are usually much higher than the returns from typical investments.
- If your credit card balance is already too large to manage with regular monthly payments, consider discussing a structured repayment plan with your bank, which sometimes offers a lower interest rate than standard credit card rates to help you get out of that trap.
Credit cards can be a useful tool when used wisely, but they can also become a source of long-term financial stress if the balance is left to accumulate without a clear repayment strategy. By entering your balance, interest rate, and actual monthly payments into this calculator, you will clearly see whether your current payment strategy is truly effective, or merely maintaining the status quo without bringing you any closer to debt freedom.
Try this calculator for free at Credit Card Repayment Calculator.
Note: The calculation above is an illustrative estimate based on a fixed APR and fixed monthly payments, for educational purposes only. The actual rates, additional charges, and terms of your credit card may vary depending on the bank, so please refer to your official statement and consult with your bank or licensed financial advisor before making any financial decisions.




