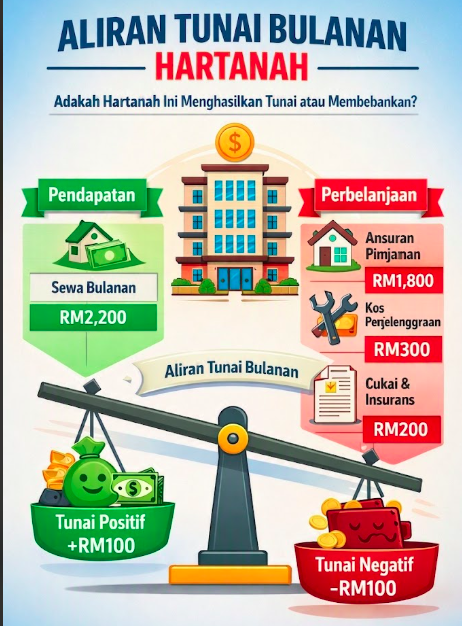
Imagine two property investors buying the same property at the same price and with the same rent. One pays cash in full, while the other takes a bank loan and only pays the down payment. Both will get the same rental yield because yield is calculated based on the full price of the property. But in terms of the actual money they take out of their pockets, their returns are vastly different. This is where the Cash-on-Cash Return (CoCR) Calculator comes into play, it measures returns based on the actual cash you invest, not the full price of the property.
Why CoCR Is Important For Leveraged Investors
Most property buyers in Malaysia don't pay cash in full, they take a bank loan and only pay the down payment and some initial costs. This is called "leverage", using bank money to control an asset much larger than your own cash. When you leverage, the rental yield (gross or net) calculated based on the full price of the property no longer reflects the actual return on the money you put in yourself.
CoCR answers the most important question for leveraged investors: "for every ringgit of cash I put out of my pocket, how much cash return do I get in a year?" This is why many professional property investors focus more on CoCR rather than rental yield alone, because it reflects the actual efficiency of their capital.
This is also why two properties with the same rental yield can have very different CoCRs. A property with high rent but also high loan repayments (due to a large loan amount) may have a low CoCR, while another property with lower rent but much lower loan repayments (due to a large down payment or a cheaper price) can have a higher CoCR. Leverage can be a double-edged sword; it can amplify your returns, but it can also amplify losses if cash flow is not managed properly.
CoCR Formula and Mechanics
The basic formula is:
- CoCR (%) = Annual Net Cash Flow / Total Cash Invested x 100
Total cash invested is not just the down payment. It includes all cash coming out of your pocket to own the property:
- Down payment
- Closing costs, such as legal fees and stamp duty
- Renovation or repair costs before it can be rented out
Annual net cash flow is calculated after deducting ALL costs including monthly loan repayments:
- Annual Net Cash Flow = (Monthly Rent x 12) - Annual Expenses - (Monthly Loan Repayment x 12)
This is a big difference compared to net rental yield, which does not deduct loan payments. CoCR takes into account the full cost of financing, which is why it is considered more "honest" for investors using bank loans.
If you don't enter the monthly instalment amount manually, this calculator will estimate it based on the Overnight Policy Rate (OPR) currently set by Bank Negara Malaysia, plus a typical bank loan margin of 1.4 percentage points. This gives a reasonable estimate of the interest rate on home loans that banks usually offer in the market.
This OPR-based approach is useful because it automatically stays up to date according to current economic conditions, without you needing to know in detail the effective rates offered by each bank. However, it is still an estimate, as different banks may offer a lower or higher margin depending on your credit profile, type of property, and current promotions. If you have already received an official offer (Letter of Offer) from a bank, it is always better to enter the actual instalment amount manually for a more accurate calculation.
Example Calculation: Property RM500,000
Say you buy a terrace house priced at RM500,000 with a down payment of RM50,000 (10%), closing costs (legal fees, stamp duty and others) RM15,000, and light renovation costs RM10,000 before it can be rented out.
Total cash invested: RM50,000 + RM15,000 + RM10,000 = RM75,000.
The remaining loan you take: RM500,000 - RM50,000 = RM450,000. Say the current OPR is 3.0%, estimated loan rate = 3.0% + 1.4% = 4.4%. At this rate, with a typical loan term (for example, 30 years), the monthly instalment for a RM450,000 loan would be around RM2,200 per month (the actual figure depends on the exact term and loan structure offered by the bank).
Say this unit is rented out at RM2,200 per month, with annual expenses (maintenance, taxes, insurance) RM4,000.
Annual net cash flow = (RM2,200 x 12) - RM4,000 - (RM2,200 x 12) = RM26,400 - RM4,000 - RM26,400 = -RM4,000 per year (in this example, the rent is almost the same as the mortgage payment, so after deducting other expenses, the cash flow becomes negative).
CoCR = (-RM4,000 / RM75,000) x 100 = -5.3%. This means, at this estimate, the property is actually costing you money every year, not generating positive returns, even though it may seem like a reasonable investment at first glance. This is a perfect example of why calculating CoCR before buying is very important, there are properties that look good in terms of price and rent but are actually losing money in terms of monthly cash flow after considering all costs.
Compare this with the gross rental yield for the same property: (RM26,400 / RM500,000) x 100 = 5.28%, a figure that looks quite attractive when viewed separately. This is why rental yield alone is not sufficient to make a purchasing decision, especially when you are using a large bank loan. CoCR reveals the monthly cash flow reality that rental yield alone cannot show.
If this investor puts down a larger down payment, say RM100,000 (20%) instead of RM50,000, the monthly instalments will be lower because the loan balance is smaller, which can change the CoCR from negative to positive, but at the cost of a higher total cash investment. This shows the basic trade-off in leveraged investment: a smaller down payment means the CoCR is more sensitive to changes in interest rates and rent, while a larger down payment provides a higher safety margin but requires a larger initial capital.
This is also why many experienced real estate investors don't just look at a single CoCR number, but test several different financing structures (10%, 20%, 30% down payments) to see which combination offers the best balance between returns and risk, according to their own financial comfort.
Tips and Common Mistakes
- Don't assume the OPR rate will remain the same forever. The interest rate can rise or fall throughout your 20 to 35-year loan period, and this will change your monthly instalments and your CoCR from time to time.
- Take into account ALL upfront costs, not just the down payment. Many investors forget about legal fees, stamp duty and renovation costs when calculating "how much money I need to put in", whereas all of these are part of the total cash invested.
- A negative CoCR doesn't necessarily mean a bad investment automatically, especially if you expect rent or property value increases in the long term. However, it's a warning signal that needs to be understood and planned for, not ignored.
- Compare CoCR across several candidate properties before deciding which one to buy, this is the fairest way to compare the actual cash efficiency of your options.
Try this calculator for free at Cash-on-Cash Return (CoCR) Calculator.
Note: All numbers in this article are illustrative estimates for planning purposes only, not financial or investment advice. Actual interest rates vary according to banks and borrower profiles, please check the latest rates with your bank before making a decision.




