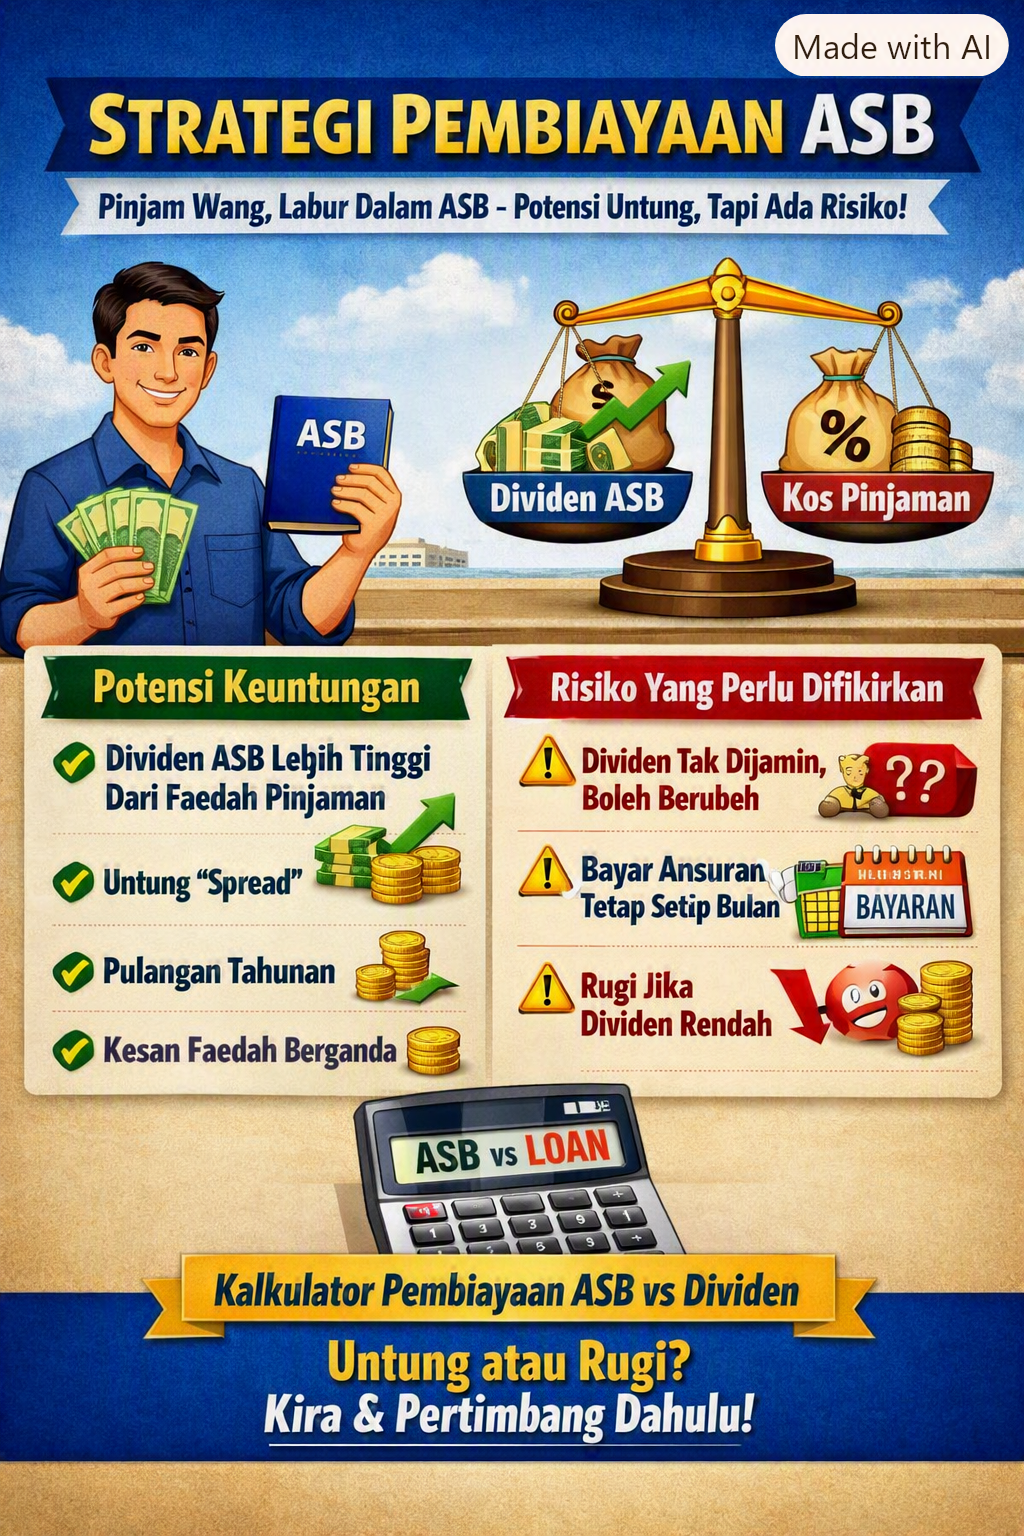
"Take an ASB loan" is one of the most popular financial strategies in Malaysia, discussed from coffee shops to online financial forums. The logic is simple: borrow money at a certain interest rate, put it into ASB, and if the ASB dividend exceeds the cost of the loan, you profit from that gap. However, this strategy is not without risk, and many overlook the risk aspect because they are too focused on the potential profit. The ASB Financing vs Dividend Calculator helps you see both sides of this picture clearly.
What Is ASB Financing Strategy
ASB financing is a specific and very popular strategy in Malaysia, where an individual takes a loan from a bank or financial institution (with an illustrative default financing interest rate of 4.5%) specifically to invest in ASB, with the gamble that the historically strong ASB dividend rate will exceed the financing cost. The concept is similar to general unit trust financing, but this strategy is specific to ASB because it is so widely practiced in Malaysia, considering the reputation of ASB as a high-dividend savings with capital generally protected.
This calculator compares the financing cost (financing interest rate and term) against the assumption or historical average ASB dividend rate over the selected financing period.
This strategy is usually offered through special financing products from banks or financial institutions that collaborate with ASNB, with an application process that is relatively easy for those who have a good credit record and a stable income. This ease of application also contributes to the popularity of this strategy, along with the historical record of ASB dividends, which have been viewed as attractive by many Malaysians.
Why This Strategy Is Popular, But Its Risks Need To Be Understood
The ASB financing strategy has remained popular for a long time because historically, ASB dividends often exceed the usual financing rates offered by financial institutions, making that gap or "spread" look like almost certain profit. However, this needs to be explained honestly, just like with general unit trust financing, ASB dividends are declared every year based on the actual performance of the fund, and they are not a guarantee.
This means that borrowers taking ASB financing bear actual debt that must be paid according to the schedule, regardless of the dividend rate declared in that year. If the dividends in a particular year are low, or lower than the financing rate, the borrower is still required to pay the full instalment, even if the profit from that year's dividends is insufficient to cover the financing costs. Therefore, anyone considering this strategy must truly understand this risk, and honestly assess their ability to pay the financing instalments even in years of low dividends, not just relying on the assumption that dividends will always be high as historical records suggest.
Another common misunderstanding is the assumption that because ASB is "safe" in terms of capital (NAV value remains RM1.00), ASB financing is also "completely safe". This confuses two different types of risks, capital risk (which is indeed low for ASB) compared to dividend income risk (which varies each year). Safe capital does not mean that dividends are guaranteed to be high every year, and the ability to pay loan instalments depends on annual dividend income, not the stable value of capital.
Calculation Example: RM80,000 Financing Over 10 Years
Suppose someone takes an ASB financing of RM80,000, at an illustrative loan interest rate of 4.5% per year, over a 10-year period, compared to the assumed historical average dividend rate of ASB.
If the assumed historical average dividend rate used is higher than 4.5%, the "spread" or positive gap, calculated as the assumed dividend rate minus 4.5%, represents the potential annual net benefit from this strategy, before considering any additional financing charges or fees. Over the 10 years, if this assumption remains consistent each year, the gap accumulates into a fairly significant benefit compared to the total financing cost that needs to be paid.
However, this is a hypothetical scenario, not a guarantee. In reality, ASB dividends change from year to year according to the official ASNB announcements each year. If, during any year within the 10-year period, the declared dividend falls below 4.5%, the borrower will still need to pay the full instalment at the 4.5% rate, even if the net profit from that year's dividend is insufficient to cover the cost. This is why borrowers need to plan with conservative assumptions, and not just based on the best-case scenario, because the obligation to repay the financing remains the same regardless of the actual dividend results for that year.
For a clearer picture of the scale of this risk, consider how the monthly instalment of RM80,000 financing at 4.5% over 10 years remains fixed every month, regardless of the dividend rate declared that year. On the other hand, the "profit" from ASB dividends is only received once a year, after the official announcement. This means, in terms of cash flow, the borrower must be able to consistently cover the monthly instalments throughout the year, without relying entirely on the expectation of end-of-year dividends to cover the cost.
Things to Consider Before Taking ASB Financing
- Don't assume high dividends will continue forever. Historical dividend rates are a guide, not a guarantee for future years.
- Understand your ability to repay in the worst-case scenario. Ask yourself, can I afford these payments if the dividend for that year is low, not just if it's high as usual?
- Understand the ASB financing eligibility limits. Banks and financial institutions set their own financing limits and eligibility criteria, check them carefully before applying.
- Avoid borrowing more than you need. The larger the financing amount, the greater the risk if dividends fall low in any year during the financing period.
- Consider combining cash and financing. Some people choose to invest part with their own cash and only a small portion through financing, to reduce overall risk.
- Re-evaluate your chosen financing term. A shorter term means higher monthly payments but lower total interest, while a longer term means lighter monthly payments but higher total interest, choose according to your personal cash flow comfort.
- Don't be entirely swayed by others' success stories. Many share the success of this strategy during high-dividend years, but rarely share their experiences during low-dividend years, get a balanced view before making a decision.
How This Strategy Differs from Unit Trust Financing
Although the basic concept of both these strategies is similar, borrowing to invest with the hope of returns exceeding financing costs, there are important differences between ASB financing and unit trust financing. ASB has a capital structure that is generally more stable than most conventional unit trust funds, because the NAV par value of RM1.00 does not fluctuate according to daily market prices. This makes the risk of capital depreciation lower for
ASB financing compared to conventional unit trust financing, although the risk of low dividends in any particular year still exists in both cases. Due to this capital stability, ASB financing is generally considered a more conservative leverage strategy compared to conventional unit trust financing, although both still carry actual debt risks that need to be understood carefully.
Try this calculator for free at ASB Financing vs Dividend Calculator.
This calculator provides illustrative estimates based on assumed financing and dividend rates, not a guarantee of actual dividend returns or financial advice. Please consult your bank or financial institution as well as ASNB officially before making actual financing decisions.




