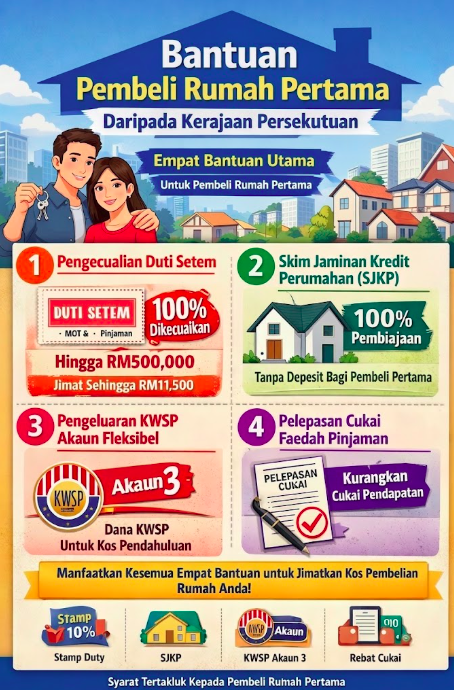
Four Major Federal Government Assistance Schemes for First-Time Homebuyers
Aside from affordable housing schemes like PR1MA or Rumah Selangorku, the federal government also offers several financial assistance schemes applicable to any first-time home purchase, whether it be affordable housing units, private developer projects, or subsale homes, as long as you meet the definition of a "first-time buyer". This article outlines four major assistance schemes introduced/extended through the latest Budget.
1. Stamp Duty Exemption (MOT & Housing Loan Agreement)
The most valuable assistance in terms of upfront cash costs. Under the latest Budget, the government has extended the 100% stamp duty exemption on:
- Transfer of Property Memorandum (MOT) — for residential properties valued up to RM500,000.
- Housing Loan Agreement — also 100% exempt for housing-related loans up to RM500,000.
This exemption applies to Sale and Purchase Agreements (SPA) signed within the specified period (extended until 31 December 2027 according to the latest Budget announcement), and can save first-time buyers up to RM11,500 in upfront cash costs — a significant amount for most young buyers. Use the Stamp Duty Transfer Calculator on this page to estimate your actual savings based on your planned house price.
Eligibility: Malaysian citizens who have never previously owned, inherited, or co-owned any residential property.
2. Housing Credit Guarantee Scheme (SJKP)
SJKP MADANI is specially designed for those often excluded from conventional bank financing due to no fixed salary slips, gig workers, small business owners, farmers/fishermen, small contractors and self-employed individuals. Key features:
- Funding up to 100% without a deposit, for the purchase of a first home (new, subsale, or auction) up to RM500,000.
- Repayment period up to 35 years.
- More flexible credit terms, total loan repayment cannot exceed 65% of monthly gross income, and no CCRIS arrears exceeding 2 months in the past 12 months.
- Alternative supporting documents are accepted (bank account statements, business licenses, fisherman registration cards, or income verification letters from local authorities/village heads/branch bank managers).
Applications are made through participating financial institutions, not directly to SJKP, check the list of participating banks at sjkp.com.my.
3. Withdrawal from Flexible Account (Account 3) of KWSP for Preliminary Costs
The three-account structure of the KWSP account (Retirement Account, Wellbeing Account, Flexible Account) allows members to withdraw part of their savings from the Flexible Account at any time for various needs, including the upfront costs of purchasing a first home, deposits, legal fees, remaining stamp duty (if any after the above exemption). This complements (not replaces) the existing Account 2 withdrawals for housing that remain in place for some housing-related purposes.
Use the Flexible Account Withdrawal Calculator (Account 3) on this page to estimate how much can be withdrawn without affecting the recommended minimum balance for emergencies.
4. Tax Exemption on Housing Loan Interest
First-time homebuyers are also eligible for a tax exemption on income tax for interest/profit from housing loans paid, subject to the limits and eligibility period set by LHDN. This reduces the annual income tax of the buyer during the early period of the loan. Check the exact amount of exemption and the current eligibility period through the official LHDN portal or your annual tax form, as these limits change according to the Budget announcements.
How to Combine All These Assistance?
These assistance programs are not exclusive to each other, a first-time homebuyer purchasing a RM350,000 PR1MA unit theoretically could enjoy all four assistance programs simultaneously: full stamp duty exemption, financing through SJKP if there is no fixed income, KWSP Flexible Account withdrawal for upfront costs, and annual tax exemption on housing loan interest. The recommended strategic order:
- Identify the eligible and suitable location for a affordable housing scheme (PR1MA/Rumah Selangorku/RUMAWIP), read the comprehensive guide to the affordable housing system.
- Estimate loan eligibility using DSR Calculator.
- Calculate the actual stamp duty savings using Stamp Duty Transfer Calculator.
- Plan your upfront cost sources, combining personal savings & withdrawal from KWSP Flexible Account.
- If you have no fixed income, check your eligibility for SJKP with the bank before applying for an affordable housing scheme, so that you know the actual financing limit in advance.
Conclusion
The first-time homebuyer assistance from the federal government is much broader than just "house price discounts" — it includes tax exemptions, loan guarantees, access to KWSP and annual tax relief, which, when combined wisely, can save tens of thousands of ringgit throughout the first home purchase process. Always check the latest eligibility criteria and periods for each assistance as they are subject to the annual budget announcements.
Disclaimer: The information in this article is provided for general reference based on the latest budget announcements and may change. Please check the MOF Benefits Portal (manfaat.mof.gov.my), LHDN and your preferred bank for the latest eligibility criteria and limits before making financial decisions.




