One of the main attractions of buying Bumiputera-status property is the price discount offered compared to non-Bumiputera units in the same project. However, many buyers are unaware that this discount rate is not a fixed national figure; it is determined separately by each state's housing/Bumiputera policy and can change from time to time.
Why Discount Rates Vary by State?
The Bumiputera property ownership policy in Malaysia is administered at the state level, not the federal level. Each State Authority, through the State Secretary's Office or a special housing unit, sets its own percentage quota of Bumiputera units in a project, and the discount rate that developers must offer for those units. This means that discounts for projects in Selangor can differ from discounts for similar projects in Johor or Pahang, even though the market prices of the properties are almost the same.
Another factor that also influences the discount rate is the type and price tier of the property itself. Affordable housing projects in the lower price range sometimes enjoy higher Bumiputera discount rates compared to premium high-tier priced projects, because the policy goals of some states focus more on increasing first-home ownership among moderate-income Bumiputera. However, this is not a uniform rule; each state and each project can set different structures according to current local market needs.
Generally, the discount rates commonly reported fall within the range of about 5% to 15% of the selling price, depending on the state, type of property, and price tier of the project in question. However, this is only a general overview, subject to the current policies of the relevant state, which may be amended at any time. Do not use this figure as a definitive reference when planning your budget.
How Are These Discounts Usually Given?
The way discounts are applied also varies according to the project structure:
- Direct price reduction — the developer sets the selling price of the Bumiputera unit lower than the market price of the same unit from the start, as stated directly in the Sale and Purchase Agreement (SPA).
- Rebate/staged exemption — some schemes only provide full discounts after certain conditions are met, or after a specific holding period has passed without the unit being resold.
- Combined with other incentives — sometimes price discounts are combined with exemptions or reductions in stamp duty/lawyer fees under certain state housing schemes.
Examples of Schemes by State
As an illustration of how this policy operates, not a complete or permanent list — Selangor has the SMART Scheme (Selangor People's Affordable Housing Scheme) which among other things provides housing ownership facilities for Selangor Bumiputera with specific conditions and rates. Other states such as Johor, Pahang, Perak and Negeri Sembilan also have their own state housing units or agencies with separate Bumiputera discount policies. Since this policy is reviewed and revised from time to time according to state budgets and local market needs, specific figures and conditions need to be confirmed directly with the relevant parties before you make a purchase decision.
How to Confirm Current Rates Before Buying
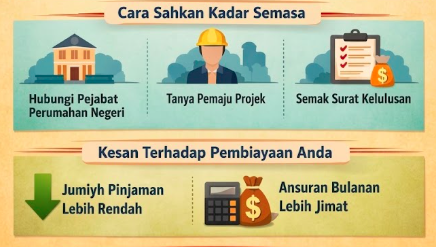
Do not rely on rumours or outdated information about discount rates. The most accurate way to find out the actual applicable rate for the unit you are interested in:
- Contact the relevant portal or state Bumiputera housing unit directly.
- Ask the project developer directly — they must comply with development approval conditions which include the approved Bumiputera discount rate for the project.
- Check the development approval letter or official project brochure, which usually states the approved discount rate for Bumiputera units in the project.
The confirmed discount rate is also important for your overall financial planning, as it changes the actual price you need to pay, which in turn affects the loan amount and monthly installments you need to be able to pay.
Impact of Discount on Your Financing
Many are unaware that the Bumiputera discount also affects your bank loan calculation, not just the on-paper price. The financing margin (Margin of Finance) approved by the bank is usually calculated based on the selling price after the discount, or sometimes based on the property valuation, whichever is lower. This means a larger discount not only saves you cash upfront, but can also reduce the loan amount you need to apply for, thereby lowering your monthly installments and the total interest/profit you need to pay throughout the loan period.
Conversely, if your state's scheme releases the discount in stages after a certain holding period (not a direct discount in the SPA), you may need to apply for a loan based on the full price without discount first, and only enjoy the financial benefits of the discount later. This is an important reason why you need to understand when and how the actual discount on your unit is given, not just the percentage, before making your financing plan.
To see how this discount affects the total cost of your purchase, try our property cost calculator at /analisis-pelaburan-ejen for a more accurate estimate based on the actual price of the unit you are interested in.




